La Vista Real Estate Investment Guide For 2026
A comprehensive resource for investors evaluating the Papillion-La Vista school district at a lower entry price, in a city that built itself a downtown from scratch
Quick answers: Top 5 most searched La Vista investment questions ▼
Migration data: Where people are moving from to La Vista ▼
In This Guide
Click on any section to navigate directly to that content
1. La Vista Market Overview
Market Fundamentals
La Vista is a compact Sarpy County city of roughly 16,600, wedged between Omaha to the north, Papillion to the south, and Bellevue to the east. It shares the Papillion-La Vista school district with its larger neighbor, which is the single most important fact for an investor here. What makes La Vista unusual is what it did after its retail core collapsed: it built itself a downtown from scratch.
Key economic indicators that define La Vista’s investment case:
- Population: Roughly 16,600, one of the most compact cities in the Omaha metro
- School District: Papillion-La Vista Community Schools, shared with Papillion
- Median Sale Price: Reported near $275,000, with list medians running toward $320,000
- Median Household Income: Reported near $78,000
- Median Gross Rent: Reported near $1,267, with houses listing from $1,795 to $2,900
- Property Tax: Sarpy County median effective rate near 1.91%, among the highest in Nebraska
Position is the other asset here. La Vista sits within roughly twenty minutes of downtown Omaha, Offutt Air Force Base, the Sarpy County data center corridor, and Papillion’s employment base. Very few small suburbs draw from four distinct employment centers at once.
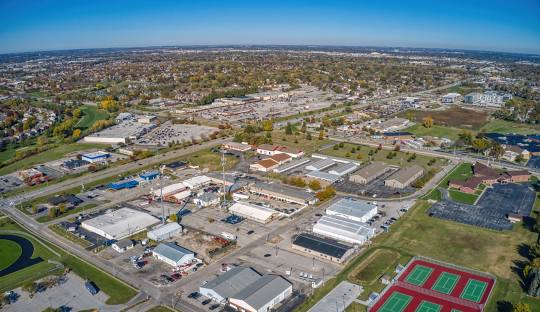
La Vista built a walkable downtown from a failed shopping center, something rare in Nebraska
2026 Economic Outlook
- City Centre continuing to lease retail, dining, and entertainment space along 84th Street
- Central Park development on the former La Vista Falls golf course connecting City Centre to the civic campus
- 84th Street corridor beautification in design, with plazas, trails, and pedestrian improvements planned
- Papillion-La Vista schools remaining the primary family demand driver
- Sarpy County property taxes near 1.91% remaining the main investor headwind
Investment Climate
Let us be precise about the comparison that brings most investors here. La Vista is genuinely better than Papillion on the numbers, and it is still not a cash flow market. A comparable 3 bedroom rents for roughly $1,845 against a median near $275,000, a rent-to-price ratio around 0.67% versus Papillion’s 0.53%. The property tax bill is lower in absolute dollars, roughly $462 per month on a $290,000 assessed value against $607 on a $370,000 Papillion property. Both of those differences are real money.
What they do not do is make the arithmetic clear at current interest rates. A La Vista single-family purchase at 25% down runs roughly $385 to $700 per month negative depending on price and rent. Small multi-family reaches roughly break even. Here is the honest ranking of what works:
- Small multi-family in the older sections reaching roughly 4.8% to 5.4% cap rates, close to break even at 25% down. The best available math in this city.
- Value-add single-family bought below the median, where the return is equity creation rather than monthly income
- Owner-occupant purchase then conversion, which removes the capital-invested problem entirely
- Low-leverage holds for investors prioritizing a stable asset in a strong district over yield
The market is also fast and thin. Homes here have sold in as little as five days, and very few trade in any given month. That combination means citywide medians swing sharply and you will be making decisions quickly on limited comparable data.
Historical Performance
| Period | Market Driver | Avg Annual Appreciation | Key Event |
|---|---|---|---|
| 2006-2013 | Retail decline along the 84th Street corridor | Flat to 2% | Walmart closes in 2006 and Baker’s in 2008, sending the corridor into decline |
| 2014-2019 | Vision 84 planning and public investment | 3-6% | Voters approve a half-cent sales tax in 2014 dedicated to 84th Street improvements |
| 2020-2022 | Low rates, City Centre construction, suburban demand | 10-15% | City Centre takes shape on the former Brentwood Crossing site |
| 2023-2024 | Rate shock, first City Centre tenants opening | 2-6% | Restaurants and retail begin opening in the new district |
| 2025-2026 | Very thin transaction volume, volatile medians | Highly variable | Monthly prints have ranged from a 17.9% decline to a 32.4% average-price increase |
Treat La Vista price data with real caution. In a city where fewer than twenty homes may sell in a month, a single unusual transaction moves the median dramatically. Recent monthly prints have shown a 17.9 percent year-over-year decline in median sale price alongside a 32.4 percent increase in average price for an overlapping period. Both figures are accurate and neither describes the market. Price off closed comparable sales for the specific neighborhood and vintage, pulled from the MLS by your agent.
Demand Drivers
- Papillion-La Vista Community Schools – The same district families pay a premium for in Papillion, available here at a materially lower entry price. This is the core investment argument for La Vista.
- City Centre and Corridor 84 – A 34-acre mixed-use district with over 200,000 square feet of retail, dining, and entertainment, plus office and residential above and two parking garages. Genuine walkability is rare in Nebraska suburbs and it supports rent.
- Central Park – The former La Vista Falls golf course being transformed into a park connecting City Centre to the existing civic campus, effectively creating a new downtown.
- Offutt Air Force Base – Fifteen to twenty minutes east, adding a military tenant layer with housing allowances that reach La Vista pricing comfortably.
- Omaha Employment – Fifteen to twenty minutes north via 84th Street and I-80, putting the entire Omaha job base within an easy commute.
- Sarpy County Growth – Data center investment and county-wide population growth continue to lift the corridor La Vista sits in the middle of.
📚 New to real estate investing? Master the fundamentals with our professional course Learn more →
2. Neighborhood Hotspots
La Vista Investment Neighborhood Map
Interactive map of La Vista’s investment areas and the surrounding Sarpy County corridor. Green stars show top hotspots, blue circles mark established markets, and orange circles highlight emerging areas.
Core Investment Neighborhoods
Detailed Submarket Analysis: La Vista and the Surrounding Corridor
| Submarket | Price Range (SFH) | Cap Rate | Growth Drivers | Best Strategy |
|---|---|---|---|---|
| North La Vista / Harrison | $215K-$285K | 4.2-5.4% | Oldest stock, lowest entry, Omaha border access | Best available La Vista math, small multi-family |
| 84th Street Corridor | $225K-$300K | 4.0-5.0% | City Centre, corridor beautification, walkability | Value-add, young professional rental |
| Brentwood / Central | $235K-$310K | 3.8-4.8% | Central Park adjacency, mature streets, redevelopment | Balanced family rental hold |
| Hillcrest / Josephine | $230K-$300K | 3.9-4.9% | Central position, rental depth, employment access | Steady family and workforce rental |
| Central Park Adjacent | $245K-$330K | 3.6-4.5% | New park amenity, civic campus connection | Appreciation angle as the park completes |
| Granville / West La Vista | $260K-$345K | 3.5-4.4% | Newer stock, professional tenants, west access | Low-maintenance hold, expect negative carry |
| Harrison Hills / S 115th | $265K-$355K | 3.4-4.3% | I-80 access, newer apartment product, west Omaha commute | Professional rental, appreciation focus |
| Southwind / Giles Road | $275K-$375K | 3.4-4.2% | Newest stock, highest La Vista rents, Papillion border | Appreciation only, weakest yields in the city |
| Ralston | $200K-$300K | 5.5-6.8% | Own district, Douglas County tax rules, lowest local entry | Better yields, different district and county |
| Papillion | $285K-$560K | 3.2-4.6% | Same district, larger newer homes, prestige address | Appreciation only, higher entry than La Vista |
| Bellevue | $185K-$400K | 4.0-6.5% | Offutt AFB, lowest corridor pricing, military demand | Military rental, VA conversion, better yields |
| Gretna | $345K-$525K | 3.3-4.2% | Fastest state growth, own district, Nebraska Crossing | Appreciation, highest Sarpy tax rate |
Expert Insight: “La Vista is the value play in this district and people oversell it. Yes, you get the same schools for a hundred and sixty thousand less than Papillion. No, that does not mean it cash flows. Sarpy County taxes are Sarpy County taxes wherever you buy in this county. What La Vista actually gives you is a smaller check every month to hold a property in a district families want, in a city that just spent a decade building itself a downtown. That is a reasonable thing to own. It is not a yield play.” – Regional investment advisor, Sarpy County
3. Property Types
| Investment Goal | Best Property Type | Best Areas | Minimum Capital |
|---|---|---|---|
| Best Available Yield | Small multi-family in the older sections | North La Vista, Harrison Street, 84th corridor | $95,000+ |
| Equity Creation | Value-add older single-family | North La Vista, 84th corridor, Brentwood | $90,000+ |
| Zero Capital Entry (VA eligible) | Owner-occupied purchase, later converted | Anywhere in the district within your BAH range | Closing costs and reserves only |
| Lowest Management | Townhome with rental-friendly HOA | Granville, Hillcrest, Southwind | $85,000+ |
| Actual Positive Cash Flow | Look outside Sarpy County | Ralston, Omaha’s Florence and South Omaha, Grand Island | $70,000+ |
Don’t guess the costs. Our Complete Renovation & Remodeling Cost Guide covers 400+ pages of project-by-project breakdowns with real contractor pricing ranges.
4. Cost Analysis
Acquisition Cost Breakdown (La Vista)
| Expense Item | Typical Cost | Example ($275,000 Property) | Notes |
|---|---|---|---|
| Down Payment | 25% (investment) | $68,750 | Roughly $40,000 less than the equivalent Papillion purchase |
| Closing Costs | 2-3% of price | $5,500-$8,250 | Title, lender fees, recording, Nebraska documentary stamp tax |
| General Inspection | $400-$650 | $500 | Mid-century stock in the north sections has more findings than newer areas |
| Sewer Line Scope | $150-$300 | $225 | Essential on anything built before 1970 in the older sections |
| Radon Test | $150-$250 | $200 | Nebraska has among the highest radon levels nationally. Mitigation $1,200-$2,500. |
| HOA Covenant Review | $0-$400 | $200 | Critical on townhomes and newer subdivisions. Rental caps are common in Sarpy County. |
| Initial Repairs | 0-10% of price | $0-$27,500 | Higher on north-side mid-century stock, minimal on newer south-side homes |
| Carry Reserves (12 months) | 12 months of negative carry | $5,000-$8,500 | Twelve months, not six. In a negative-carry market you fund the shortfall. |
| TOTAL MINIMUM ENTRY | ~29-40% of value | $80,325-$110,125 | Meaningfully below Papillion, which runs $126,575 to $170,275 |
Sample Cash Flow Analysis: North La Vista Value-Add
Purchase price $235,000, bought below the citywide median in the older north section. Renovation $25,000. All-in cost $260,000. Post-renovation appraised value $290,000. Leased to a district-seeking family at $1,845 per month. Modeled at 25% down with professional management.
| Item | Monthly | Annual | Notes |
|---|---|---|---|
| Gross Rent | $1,845 | $22,140 | 3BR renovated, consistent with live La Vista house listings |
| Less Vacancy (5%) | -$92 | -$1,107 | Low, because district-seeking families stay for years |
| Property Taxes | -$462 | -$5,539 | 1.91% of the reassessed $290,000 value. Twenty five percent of gross rent. |
| Insurance | -$190 | -$2,280 | Landlord policy. Nebraska hail claims have pushed premiums up sharply. |
| Property Management (9%) | -$166 | -$1,992 | Standard Sarpy County residential rate |
| Maintenance + CapEx (8%) | -$148 | -$1,771 | Reduced because major systems were just replaced |
| Net Operating Income | $788 | $9,451 | Before mortgage |
| Mortgage ($176,250 loan, 25% down on purchase price, 7.0%, 30yr) | -$1,173 | -$14,072 | Principal and interest only, renovation paid in cash |
| CASH FLOW | -$385 | -$4,621 | Negative, though $119 per month better than the equivalent Papillion deal |
| Cap Rate | 3.63% | NOI divided by $260,000 all-in cost | |
| Equity Created | $30,000 | $290,000 appraised value less $260,000 all-in cost | |
| Same deal, 20% down and self-managed | -$312 | -$3,744 | Better, and still negative |
Now the comparison that matters, run honestly. The equivalent Papillion value-add, at $300,000 plus $30,000 renovation renting for $2,250, produces about $993 of monthly NOI against a $1,497 payment, roughly $504 per month negative at a 3.61% cap rate. La Vista’s version runs $385 negative at a 3.63% cap. So La Vista is roughly $119 per month better and requires about $23,000 less capital to enter. Both are negative-carry deals in the same school district and the same county.
Where La Vista pulls genuinely ahead is small multi-family. A duplex at $255,000 plus $25,000 renovation grossing $2,300 from two units produces roughly $1,112 of monthly NOI against a $1,272 payment, about $161 per month negative at a 4.76% cap. Push the rents to $1,250 per unit and it reaches essentially break even at a 5.43% cap. That is the best outcome available anywhere in the Papillion-La Vista school district, and it does not exist in Papillion at all because the small multi-family stock there is nearly nonexistent.
Expert Insight: “The tax line is where La Vista wins over Papillion, and it is not because the rate is different. Sarpy County is Sarpy County. It is because you are paying one point nine one percent on a two hundred ninety thousand dollar house instead of on a three hundred seventy thousand dollar house. Four sixty two a month versus six oh seven. Same county, same levy, eighteen hundred dollars a year difference, entirely because the assessed value is lower. Buy the cheaper house in the same district and the tax bill follows you down.” – Property tax consultant, Sarpy County
5. Legal Framework
⚠️ Critical La Vista Compliance Notice
Nebraska landlord-tenant law is straightforward and La Vista adds little on top. Three items do matter here: homeowners association rental restrictions on townhomes and newer subdivisions, the Servicemembers Civil Relief Act given Offutt proximity, and mixed-use zoning around the redeveloped 84th Street corridor. Statutes, ordinances, and covenants change. This guide is an overview only. Confirm current requirements with a Nebraska-licensed attorney, the City of La Vista, and the specific HOA before acquiring rental property.
Nebraska and La Vista Regulations
Residential tenancies in La Vista are governed by the Nebraska Uniform Residential Landlord and Tenant Act, Nebraska Revised Statutes 76-1401 through 76-1449, plus local and private restrictions:
- HOA Rental Restrictions: Common across Sarpy County townhome communities and newer subdivisions. Covenants may cap the number of rentals, impose waiting lists, require board approval of tenants, or set minimum lease terms. They are enforceable and they can make a property unrentable. Obtain the full recorded covenants during your inspection period.
- Mixed-Use Zoning: The 84th Street Redevelopment Plan established mixed-use residential zoning behind the commercial frontage along the corridor. If you are buying anything near City Centre, confirm the zoning classification and what it permits.
- Servicemembers Civil Relief Act: With Offutt fifteen to twenty minutes east, some La Vista tenants are servicemembers. SCRA allows early lease termination on qualifying orders and cannot be waived by lease.
- No Rent Control: Nebraska has no statewide rent control and La Vista has not adopted one. Nebraska Revised Statute 76-1490 requires at least sixty days written notice of a rent increase.
- No Just Cause Requirement: A landlord may decline to renew an expiring lease, and may terminate a month-to-month tenancy with at least 30 days written notice under Nebraska Revised Statute 76-1437(2).
- Security Deposits: Capped at one month’s rent, plus up to an additional one quarter month as a pet deposit. Return within 14 days with an itemized statement, or face liability of 1.5 times any amount wrongfully withheld.
- Nonpayment Notice: 3 day written notice to pay or vacate under Nebraska Revised Statute 76-1431(2). Lease violations generally get 14 days to cure with termination in 30.
- No Citywide Registration: La Vista does not operate a rental registration program equivalent to Omaha’s Ordinance 41767 or Lincoln’s apartment licensing. The city does enforce property maintenance and building codes.
Compliance Best Practices
La Vista compliance is light on public regulation. The discipline is in covenants, valuation, and tenant profile:
- Read the Covenants Before You Offer: Especially on townhomes and anything built in the last twenty five years. A rental cap can strand your capital in a property you cannot lease.
- Verify the Attendance Zone: Papillion-La Vista Community Schools serves both cities, but confirm the specific school assignment on the parcel record, since that is what your tenant is actually buying.
- Use an SCRA-Aware Lease: Have your Nebraska attorney include a proper military clause rather than an unenforceable waiver.
- Budget the Carry, Not Just the Reserve: In a negative-carry market, twelve months of shortfall funding is the realistic reserve standard.
- Model the Reassessment: Sarpy County assesses annually as of January 1 at or near full market value. Your renovation raises next year’s bill.
- Protest the Assessment: In one of Nebraska’s highest-rate counties, a successful protest to the County Board of Equalization is worth more than a rent increase. Appeals go to the Nebraska Tax Equalization and Review Commission.
- Photograph Everything: With the 1.5x deposit penalty, a dated photo set at every move-in and move-out is essential.
Useful La Vista Resources
- City of La Vista, for permit, code, zoning, and redevelopment questions
- Sarpy County Assessor and Sarpy County Treasurer
- Papillion-La Vista Community Schools, for attendance zone verification
- Sarpy County Register of Deeds, for recorded covenants and restrictions
- Nebraska Revised Statutes 76-1401 to 76-1449 (NURLTA)
- Nebraska Tax Equalization and Review Commission, for assessment appeals
| Regulation | La Vista Situation | Nebraska State Law | Investor Impact |
|---|---|---|---|
| HOA Rental Caps | Common on townhomes and newer subdivisions | Covenants are enforceable private contracts | Can make a property unrentable. Read covenants before offering. |
| Early Lease Termination | SCRA applies to Offutt-connected tenants | Standard lease terms otherwise apply | Federal law overrides your lease for military tenants on orders |
| Registration | No citywide program | No statewide registration program | Lower public compliance burden than Omaha or Lincoln |
| Eviction | No local just cause ordinance | 3 day notice for nonpayment, 14/30 for lease breach | Fast process, though rarely needed with this tenant profile |
| Rent Increases | No cap, but new City Centre supply competes | At least 60 days written notice (76-1490) | Legal freedom, real market constraint from new apartment product |
| Property Tax | Sarpy County median effective rate near 1.91% | State median near 1.39%, assessed at or near full market value | Roughly 25% of gross rent on a typical La Vista rental |
6. Step-by-Step La Vista Investment Playbook
Define Your La Vista Strategy
Four approaches work here, ranked roughly by how well the numbers hold up:
Small Multi-Family in the Older Sections
The best math available anywhere in the Papillion-La Vista district. A renovated duplex reaches roughly break even at a 4.8% to 5.4% cap. This stock is scarce and it does not exist in Papillion at all, which is the real La Vista advantage.
Value-Add Equity Creation
Buy older north-side stock below the citywide median, renovate, and take the return as equity. The sample deal in this guide created $30,000 of equity while running $385 per month negative, and required about $23,000 less capital than the Papillion equivalent.
Owner-Occupy Then Convert
The most realistic path for most individuals. Buy as a primary with low or zero down financing, live in it, convert when you move. With Offutt nearby, VA at zero down is genuinely available to a meaningful share of buyers in this market.
Low-Leverage District Hold
Buy with 40 percent down or cash and take a 3.6 percent to 5 percent unlevered return against strong tenant quality, long tenancies, and a city actively investing in its own downtown. Defensive rather than exciting.
Build Your La Vista Team
Small city, fast market, and a professional bench largely shared with Papillion and Bellevue. The team you need is a Sarpy County team.
- Sarpy County Investor Agent: Someone who covers La Vista, Papillion, and Bellevue together, knows which subdivisions carry rental caps, and can tell you when a duplex is coming available in the older north sections.
- Nebraska Real Estate Attorney: For covenant review, entity structure, NURLTA-compliant leases, and an SCRA-aware military clause.
- Property Tax Consultant: Load-bearing in a county with a 1.91 percent effective rate. A successful protest can exceed a year of rent increases.
- Property Manager with Family-Rental Experience: This is a long-tenancy market. You want a manager good at renewals, not one built for constant leasing volume.
- Real Estate CPA: In a negative-carry market, the tax treatment of losses and your depreciation schedule matter more than usual to the overall return.
- Insurance Agent: Nebraska hail exposure drives premiums. Get a quote before you are under contract.
Expert Tip: Ask any prospective La Vista agent one question: “When was the last time a duplex traded in the older north section, and who bought it?” An agent who works this market answers with specifics. The small multi-family stock here is the only thing in the entire Papillion-La Vista district that comes close to breaking even, and it is thin enough that knowing who owns it is the whole advantage.
La Vista-Specific Due Diligence
Standard due diligence plus the items that specifically bite in this market:
Physical Due Diligence
- Radon test, since Nebraska sits in one of the highest radon zones nationally
- Sewer lateral scope on north-side and central stock built before 1970
- Roof condition and hail claim history, which drives Nebraska insurance pricing
- Basement drainage and grading, a recurring finding in Sarpy County soils
- Furnace, water heater, and AC age on mid-century north-side homes
- Electrical service capacity in older homes never updated for modern loads
- Egress window compliance in any finished basement counted as a bedroom
Regulatory and Financial Due Diligence
- Obtain and read the full HOA covenants on townhomes and newer subdivisions, checking for rental caps
- Confirm current HOA dues and any pending special assessment
- Verify the Papillion-La Vista attendance zone on the parcel record
- Confirm zoning classification, especially near the 84th Street mixed-use redevelopment area
- Run the Sarpy County tax estimator on the specific parcel, not a county average
- Model the post-renovation reassessment at your after-repair value
- Price off closed comparable sales, since monthly medians here swing wildly on low volume
Acquire, Lease, and Operate
La Vista is a very competitive, very thin market. Homes have sold in as little as five days and very few trade in any given month, so your financing and your team need to be ready before you write.
Winning Offers in La Vista
- Buy what owner-occupants will not. Your competition here is families buying a school district, and they will outbid an investor on a clean, updated house every time. Dated properties in the north sections are where you have an edge.
- Buy in the off-season. August through December is the softer window, and it lets you renovate ahead of the spring and summer family leasing season.
- Never waive the covenant review. Price and inspection are negotiable. Whether you can legally rent the property is not.
- Underwrite the reassessment. Your renovation raises next January’s tax bill in a county assessing at or near full market value.
- Do not price off a citywide median. With fewer than twenty sales a month, La Vista medians have printed a 17.9 percent decline and a 32.4 percent increase over overlapping periods. Use MLS comps only.
The Leasing Calendar
- March to May: Families begin searching for a summer move so children start the school year in the district.
- June to August: Peak leasing, strongest rents, fastest fill.
- September to November: Sharply slower. Families avoid mid-year moves.
- December to February: Weakest window. Avoid a unit coming available here if you can control it.
- Watch City Centre supply: New residential above the retail district competes for young professional tenants, so track what is leasing there before you set your rent.
Typical La Vista Management Fees
- Single-family management: 8-10% of monthly rent
- Small multi-family management: 7-9% of monthly rent
- Townhome management: 8-10%, plus HOA coordination in some cases
- Leasing fee: 50-100% of one month’s rent
- Lease renewal fee: $150-$300 per renewal, worth it in a long-tenancy market
7. Financing Options for La Vista
| Loan Type | Down Payment | Rate Premium | Best For | La Vista Note |
|---|---|---|---|---|
| Conventional Investment | 20-25% | +0.5-0.75% | W-2 income, good credit, 1-4 unit purchases | $68,750 down on a median purchase, roughly $40,000 less than Papillion |
| VA Loan | 0% | Competitive, no PMI | Eligible service members who will owner-occupy | Genuinely relevant with Offutt fifteen minutes east, and La Vista pricing fits most BAH tiers |
| Owner-Occupant Conventional | 3-5% | Standard + PMI | Buying a primary you may later convert | The most realistic path to a La Vista rental for a non-veteran individual |
| House Hacking (FHA) | 3.5% | Standard + MIP | Owner-occupying one unit of a 2-4 unit property | Works where duplex stock exists in the older north sections, which is limited |
| Local Portfolio Loan | 20-30% | +0.75-1.75% | Multiple properties, self-employed, blanket loans | Nebraska community banks understand this corridor’s carry profile |
| DSCR Loan | 25-30% | +1.0-2.0% | Investors avoiding income verification | Fails on single-family at roughly 0.67x. A duplex reaches about 0.87x, still short of 1.0x. |
| 203(k) / Renovation Loan | 3.5-25% | +0.25-1.0% | Buying and renovating in one loan | Good fit for the north-side value-add strategy |
La Vista Financing Reality: The DSCR math tells the story of this market precisely. A La Vista single-family producing roughly $788 of monthly NOI against a $1,173 payment lands near 0.67x coverage, better than Papillion’s 0.66x and still well short of the 1.0x most programs require. A La Vista duplex at roughly $1,112 NOI against a $1,272 payment reaches about 0.87x, which is the closest anything in the Papillion-La Vista school district gets. For comparison, a Grand Island duplex clears at about 1.11x. If your plan requires DSCR financing, La Vista is not where you execute it. If you have W-2 income and want this district, La Vista is the cheapest way in.
8. Frequently Asked Questions

Knowledge Quiz: La Vista Real Estate Investment
Open Quiz
5 quick questions on what you just learned about La Vista investing
1) How does a La Vista value-add deal compare to the equivalent Papillion deal?
Answer: B
La Vista runs about $385 per month negative at a 3.63% cap. Papillion runs about $504 negative at a 3.61% cap. The cap rates are nearly identical. La Vista’s advantages are a lower monthly shortfall and a materially lower capital requirement, not a fundamentally different return profile.
2) What is the one property type where La Vista genuinely beats Papillion?
Answer: C
A renovated La Vista duplex reaches roughly break even at a 4.8% to 5.4% cap rate, the best outcome available anywhere in the Papillion-La Vista school district. Papillion is overwhelmingly detached owner-occupied housing with a homeownership rate near 65 percent, so that stock effectively does not exist there.
3) What happened to the 84th Street corridor and how did La Vista respond?
Answer: A
Walmart closed in 2006 and Baker’s in 2008, sending the corridor into decline. La Vista developed the Vision 84 plan, voters approved a half-cent sales tax in 2014 dedicated to 84th Street public improvements, and tax increment financing helped fund a 34-acre mixed-use City Centre plus Central Park on the former golf course.
4) Why is La Vista’s property tax bill lower than Papillion’s if they are in the same county?
Answer: D
Sarpy County’s effective rate near 1.91% applies in both cities. The difference is roughly $462 per month on a $290,000 La Vista property versus $607 on a $370,000 Papillion property. Buy the cheaper house in the same district and the tax bill follows you down.
5) Why should you never underwrite a La Vista deal off a citywide median price?
Answer: B
Recent prints have shown a median sale price down 17.9 percent year over year alongside an average price up 32.4 percent over an overlapping period. Both are accurate and neither describes the market. Have your agent pull closed MLS comps for the specific neighborhood, vintage, and size.
Work With a Local Expert in La Vista
We are building a verified network of real estate professionals across every market we cover.

About Our Expert Network
We are finalizing partnerships with verified real estate professionals across every market featured on Builds and Buys. Each expert in our network is selected for their hands-on investment experience, local market knowledge, and commitment to helping buyers and investors make sound decisions.
Our local specialists offer:
- Proven experience with investment and income-producing properties
- Deep knowledge of local pricing, rental yields, and neighborhood dynamics
- Guidance on financing, legal structure, and due diligence
- Access to off-market and pre-market opportunities
- Full transaction support from search through closing
- Ongoing portfolio and property management referrals
Services Covered
- Property sourcing and acquisition
- Investment analysis and underwriting
- Buyer representation
- Market comparables and valuations
- Short-term and long-term rental strategy
- Value-add and renovation guidance
- Legal and title referrals
- Financing and lender connections
- Property management referrals
- Insurance and inspection referrals
- 1031 exchange coordination
- Exit strategy planning
Get Connected or Join Our Network
Looking for a local expert to help with your investment? Reach out and we will connect you with the right professional for your market and strategy.
Are you a real estate professional with a track record working with investors? We are always expanding our network of verified local experts.
Contact us at support@buildsandbuys.com
Find Specialized La Vista Real Estate Professionals
Ready to Invest in La Vista?
La Vista is the cheapest way into the Papillion-La Vista school district, and that is a real advantage worth roughly $119 per month and $23,000 of capital against the equivalent Papillion purchase. It is not, however, a cash flow market. Sarpy County’s property tax rate applies here the same as everywhere else in the county, and single-family purchases run negative at current interest rates. Where La Vista genuinely stands alone is small multi-family in the older north sections, which reaches roughly break even at a 4.8 to 5.4 percent cap and does not meaningfully exist anywhere else in this district. Add a city that spent a decade turning a failed shopping center into a walkable downtown, four employment centers within twenty minutes, and tenants who stay for years, and you have an asset worth owning for the right reasons.
Continue Your Research
Nebraska State Guide
See how La Vista compares to Omaha, Lincoln, Papillion, and other Nebraska markets.
Papillion City Guide
The same school district at a higher entry price, with the full side-by-side comparison.
144-Lesson Course
University-level real estate education covering financing, law, strategy, and management.
For further guidance, explore our State-by-State Investor guides, browse our expert articles, or follow our Step-by-Step Investment Guide.