Norfolk Real Estate Investment Guide For 2026
A comprehensive resource for investors evaluating northeast Nebraska’s regional hub, where small multi-family produces the strongest returns in this entire series
Quick answers: Top 5 most searched Norfolk investment questions ▼
Migration data: Where people are moving from to Norfolk ▼
In This Guide
Click on any section to navigate directly to that content
1. Norfolk Market Overview
Market Fundamentals
Norfolk sits at the junction of the Elkhorn and North Fork rivers in northeast Nebraska, at the intersection of U.S. Routes 81 and 275, roughly 100 miles north of Omaha and about an hour from Sioux City. It is the largest city in Madison County and the biggest city for a considerable distance, which makes it the commercial, medical, and retail hub for a large rural region. For investors it produces the strongest returns in this entire Nebraska series.
Key economic indicators that define Norfolk’s investment case:
- Population: Roughly 25,000, the largest city in Madison County
- Major Employers: Nucor Steel, Faith Regional Health Services, Northeast Community College, Norfolk Iron and Metal, medical device manufacturing, Norfolk Public Schools
- Median Sale Price: Six-month closings reported near $240,000
- House Rents: Roughly $1,600 to $2,195 for three and four bedroom homes
- Apartment Rents: One bedroom averaging near $990, two and three bedroom from about $995 to $2,095
- Rent-to-Price Ratio: Near 0.69% at the median, the best in this series
The city runs a substantial park system including Skyview Park and Skyview Lake plus Ta-Ha-Zouka Park, with waterfront trails and recreational facilities. The historic downtown district along Norfolk Avenue supports local shops and restaurants. Norfolk is also known as Johnny Carson’s hometown.
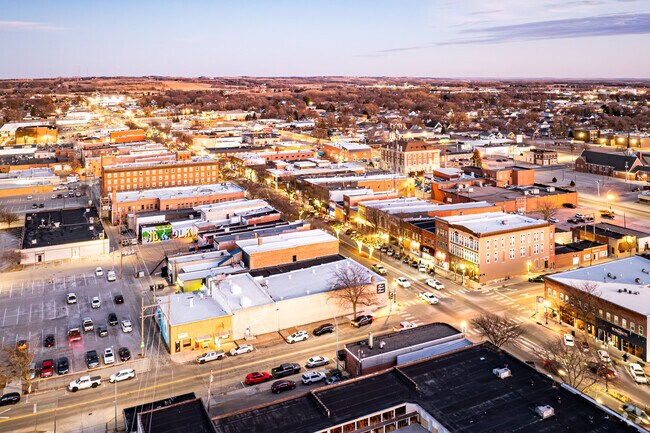
Norfolk produces the strongest small multi-family returns of any market in this series
2026 Economic Outlook
- Nucor Steel and metals manufacturing anchoring industrial employment
- Faith Regional Health Services serving a wide northeast Nebraska catchment
- Northeast Community College adding a student and staff rental layer
- Regional retail hub status drawing consistent traffic from surrounding rural counties
- Very thin transaction volume, roughly 26 county sales a month, producing volatile published medians
Investment Climate
Norfolk posts the strongest numbers in this series, and the arithmetic behind that is not complicated. A renovated fourplex at $325,000 all-in grossing $3,500 produces roughly $601 per month positive at a 7.47% cap rate and clears DSCR at about 1.42x. Both figures lead every other Nebraska market we have modeled, including Kearney and Fremont.
Three things drive it:
- A rent-to-price ratio near 0.69% at the median. A three bedroom house rents for roughly $1,650 against a $240,000 median. Compare that to Gretna’s 0.59% at $440,000, or Papillion’s 0.53% at $435,000.
- A Madison County property tax rate well below the Omaha metro. More of every rent dollar survives to the bottom line than in Douglas County at roughly 2.11% or Sarpy at 1.97%.
- Genuinely low entry prices on older multi-family. A duplex in the $195,000 range plus renovation is achievable here in a way it simply is not in the eastern metros.
Even the single-family math nearly works. A value-add house at $190,000 all-in renting for $1,600 comes within about $21 a month of break even at 25% down, which a self-managed owner clears outright. That is the closest to neutral any single-family deal gets in this series.
The honest counterweight is distance. At roughly 100 miles from Omaha, Norfolk is the most remote market we cover in Nebraska. That means fewer comparable sales, a thinner resale market, a smaller professional bench, and a real drive if you want to see your own property. Those are not reasons to avoid Norfolk. They are reasons to hold longer and keep deeper reserves.
Historical Performance
| Period | Market Driver | Avg Annual Appreciation | Key Event |
|---|---|---|---|
| 2010-2015 | Steady manufacturing and regional hub economy | 1-3% | A quiet market with essentially no outside investor attention |
| 2016-2019 | Healthcare expansion, stable industrial base | 2-4% | Regional medical capacity grows, drawing clinical staff to the area |
| 2020-2022 | Low rates, buyers priced out of eastern metros | 7-12% | Out-of-area buyers begin discovering northeast Nebraska pricing |
| 2023-2024 | Rate shock offset by very low entry prices | 3-6% | Rents rise while purchase prices stay low, improving yields for buyers |
| 2025-2026 | Extremely volatile prints on thin volume | Unreliable at the county level | Madison County medians printed up 57.4% in one month and up 25.8% in another, on roughly 26 sales |
Norfolk price data is the least reliable in this series and the reason is arithmetic. Roughly 26 homes sell in Madison County in a typical month, and recent sales have ranged from $152,630 to $800,000 within the same period. A single large transaction moves the county median by tens of percent. Reported figures include a Norfolk home value near $211,700, a six-month closing median near $240,000, a Madison County median sale near $276,727, and a monthly county print of $315,000. County figures also blend in smaller towns like Madison, Battle Creek, and Tilden. Price off closed comparable sales for the specific neighborhood and property type, and treat any single monthly percentage change as noise.
Demand Drivers
- Nucor Steel and Metals Manufacturing – Industrial employment at wages that support workforce rents, with Norfolk Iron and Metal adding further capacity. Shift workers rent rather than buy, which is the foundation of the local rental market.
- Faith Regional Health Services – The healthcare anchor for northeast Nebraska, employing clinical and administrative staff and drawing traveling clinicians who need furnished mid-term housing.
- Northeast Community College – Adds students and staff to the rental pool and creates a partial academic leasing cycle in the surrounding blocks.
- Regional Retail Hub Status – As the biggest city for a considerable distance, Norfolk captures retail, dining, and service spending from a wide rural catchment, supporting a substantial service employment base.
- Medical Device Manufacturing – Additional industrial employment diversifying the local base beyond steel and metals alone.
- Highway Junction Position – The intersection of U.S. Routes 81 and 275 anchors regional traffic, logistics, and hospitality employment.
📚 New to real estate investing? Master the fundamentals with our professional course Learn more →
2. Neighborhood Hotspots
Norfolk Investment Neighborhood Map
Interactive map of Norfolk’s investment areas and the surrounding northeast Nebraska region. Green stars show top hotspots, blue circles mark established markets, and orange circles highlight emerging areas.
Core Investment Neighborhoods
Detailed Submarket Analysis: Norfolk and Northeast Nebraska
| Submarket | Price Range | Cap Rate | Growth Drivers | Best Strategy |
|---|---|---|---|---|
| Downtown / Norfolk Avenue | $130K-$265K | 6.5-7.8% | Densest older stock, walkable core, lowest entry | Small multi-family value-add, highest returns in the series |
| Near Northeast Community College | $140K-$250K | 6.0-7.5% | College demand, partial academic cycle | Mixed student and workforce leasing |
| Northern Heights | $145K-$255K | 5.8-7.2% | Established neighborhood, industrial and clinical workers | Value-add workforce rental, long tenancies |
| Near Faith Regional Health | $160K-$280K | 5.8-7.0% | Regional healthcare, traveling clinician demand | Furnished mid-term, stable long-term hold |
| Westside | $155K-$275K | 5.6-6.9% | Established rental area, hospital and retail access | Balanced hold, small multi-family where available |
| South Norfolk / Ta-Ha-Zouka | $150K-$270K | 5.4-6.6% | Park access, mixed vintages, river proximity | Workforce rental, verify flood zone near the river |
| Highway 275 / East Corridor | $155K-$265K | 5.4-6.6% | Commercial corridor, retail and service employment | Steady workforce rental, regional access |
| Skyview Lake / Park Area | $200K-$340K | 4.4-5.4% | Park and lake amenity, family demand | Family rental, moderate yields |
| Northwest Norfolk | $260K-$420K | 3.6-4.4% | Newest construction, strongest owner-occupant demand | Buy to live in, not to rent out |
| Madison | $110K-$210K | 6.5-8.2% | County seat, very low entry prices | Cash flow hold, thin comps and slow resale |
| Wayne | $125K-$235K | 6.5-8.0% | Wayne State College, four-year student demand | Student rental, small-town pricing |
| Columbus | $165K-$340K | 5.0-6.8% | Manufacturing base, larger market than Norfolk | Similar thesis, slightly higher entry, deeper inventory |
Expert Insight: “Norfolk gives you the best numbers in this state and I will not pretend otherwise. A fourplex here pays six hundred a month and covers debt at one point four two. But understand what you are buying. Twenty six houses sell in this whole county in a month, and last month they ranged from a hundred fifty two thousand to eight hundred thousand. There is no such thing as a reliable comp here without an agent pulling actual closed sales on your block. And when you go to sell, your buyer is another investor from Omaha or Sioux City, not a bidding war. Buy it for the cash flow and plan to own it for a decade.” – Regional investment advisor, northeast Nebraska
3. Property Types
| Investment Goal | Best Property Type | Best Areas | Minimum Capital |
|---|---|---|---|
| Maximum Cash Flow | Renovated fourplex | Downtown, Northern Heights, near the college | $120,000+ |
| Best Entry-Level Deal | Renovated duplex | Downtown, Northern Heights, Westside | $90,000+ |
| Highest Cash-on-Cash | Furnished mid-term near the hospital | Near Faith Regional Health, Westside | $65,000+ including furnishings |
| First Investment / House Hack | Owner-occupied duplex using FHA | Downtown, Northern Heights | $11,000+ |
| Equity Creation | Value-add older single-family | Northern Heights, downtown blocks, South Norfolk | $75,000+ |
Don’t guess the costs. Our Complete Renovation & Remodeling Cost Guide covers 400+ pages of project-by-project breakdowns with real contractor pricing ranges.
4. Cost Analysis
Acquisition Cost Breakdown (Norfolk)
| Expense Item | Typical Cost | Example ($285,000 Fourplex) | Notes |
|---|---|---|---|
| Down Payment | 25% (investment) | $71,250 | Four income-producing units for less than a Papillion single-family down payment |
| Closing Costs | 2-3% of price | $5,700-$8,550 | Title, lender fees, recording, Nebraska documentary stamp tax |
| General Inspection | $600-$1,000 | $800 | Multi-family inspections cost more and are essential on older stock |
| Sewer Line Scope | $150-$300 | $225 | Essential. Most affordable Norfolk multi-family is genuinely old. |
| Radon Test | $150-$250 | $200 | Nebraska has among the highest radon levels nationally. Mitigation $1,200-$2,500. |
| FEMA Flood Determination | $25-$150 | $100 | Norfolk sits at a two-river junction. Cheap insurance against an expensive surprise. |
| Zoning and Occupancy Verification | $0-$500 | $250 | Critical on any property with more units than zoning obviously supports |
| Initial Repairs | 10-16% of price on older stock | $28,500-$45,000 | Utility separation and mechanical work dominate multi-family scopes |
| Reserves (6 months) | 6 months expenses | $8,000-$12,000 | Deeper reserves are warranted given the remote location and thin contractor bench |
| TOTAL MINIMUM ENTRY | ~40-48% of price | $114,925-$138,375 | The lowest fourplex entry in this series, for the highest returns in it |
Sample Cash Flow Analysis: Downtown Norfolk Value-Add Fourplex
Purchase price $285,000. Renovation $40,000. All-in cost $325,000. Post-renovation appraised value $365,000. Four units leased at $875. Modeled at 25% down with professional management.
| Item | Monthly | Annual | Notes |
|---|---|---|---|
| Gross Rent (4 × $875) | $3,500 | $42,000 | Renovated 2BR units, consistent with local listings from $995 to $1,395 |
| Less Vacancy (6%) | -$210 | -$2,520 | Reasonable given industrial and healthcare employment depth |
| Property Taxes | -$502 | -$6,020 | Modeled at 1.65% of the reassessed $365,000. Verify the parcel record, see the note below. |
| Insurance | -$170 | -$2,040 | Landlord policy. Nebraska hail exposure drives premiums statewide. |
| Property Management (9%) | -$315 | -$3,780 | Essential rather than optional at this distance from the metros |
| Maintenance + CapEx (8%) | -$280 | -$3,360 | Older building, so budget honestly even after renovation |
| Net Operating Income | $2,023 | $24,280 | Before mortgage |
| Mortgage ($213,750 loan, 25% down on purchase price, 7.0%, 30yr) | -$1,422 | -$17,068 | Principal and interest only, renovation paid in cash |
| CASH FLOW | +$601 | +$7,212 | The strongest figure in this entire Nebraska series |
| Cap Rate | 7.47% | NOI divided by $325,000 all-in cost | |
| Cash-on-Cash Return | 5.76% | On $125,250 total cash invested including renovation and reserves | |
| Equity Created | $40,000 | $365,000 appraised value less $325,000 all-in cost |
The same city, by property type. A duplex at $195,000 plus $35,000 renovation grossing $2,300 produces about $1,237 of NOI against a $973 payment, roughly $264 per month positive at a 6.45% cap. A value-add single-family at $155,000 plus $35,000 renovation renting for $1,600 produces about $753 of NOI against a $773 payment, roughly $21 per month negative at a 4.75% cap, which a self-managed owner turns positive. A median retail house at $240,000 renting for $1,650 runs about $441 negative at a 3.78% cap.
Norfolk against the rest of the series. On comparable renovated fourplexes: Norfolk 7.47% cap and $601 positive, Kearney 7.27% and $576, Fremont 7.21% and $546, Grand Island 6.74% and $375. Norfolk leads all of them. What Norfolk does not lead on is liquidity, professional depth, or proximity to anything. Fremont delivers 96% of Norfolk’s cash flow 35 miles from Omaha instead of 100. Which matters more depends entirely on whether you plan to be hands-on.
Expert Insight: “We modeled Madison County at one point six five percent in this guide because that is a reasonable working figure for a northeast Nebraska county, but do not take our number to a closing table. Levies vary by school district and by taxing entity, and the difference between one point five and one point eight on a three hundred sixty five thousand dollar building is about eleven hundred dollars a year. In a deal netting seven thousand, that is a sixth of your cash flow. Pull the parcel record from the county assessor before you write the offer.” – Property tax consultant, northeast Nebraska
5. Legal Framework
⚠️ Critical Norfolk Compliance Notice
Nebraska is a landlord friendly state and Norfolk adds little on top. Two items decide whether the strategies in this guide are legal on a given property: zoning and permitted unit count, and occupancy limits governing unrelated tenants. A third, floodplain status, matters because the city sits at a two-river junction. Statutes and ordinances change. This guide is an overview only. Confirm current requirements with a Nebraska-licensed attorney and the City of Norfolk before acquiring rental property.
Nebraska and Norfolk Regulations
Residential tenancies in Norfolk are governed by the Nebraska Uniform Residential Landlord and Tenant Act, Nebraska Revised Statutes 76-1401 through 76-1449, plus the City of Norfolk municipal code:
- Zoning and Unit Count: Determines whether a parcel permits two, three, or four units, which decides whether the small multi-family strategy in this guide is legal on that property. Confirm zoning and any existing legal nonconforming status in writing before you close.
- Occupancy Limits: Governs how many unrelated tenants may share a dwelling, which matters for any by-the-room plan near Northeast Community College. Bedroom count does not automatically equal legal occupancy.
- Floodplain Regulations: Norfolk sits at the junction of the Elkhorn and North Fork rivers. Communities in the National Flood Insurance Program adopt floodplain management ordinances governing construction and substantial improvement in mapped zones. Confirm status before planning any major renovation.
- Housing Programs: The city operates a Norfolk Housing Agency administering Section 8 and related programs. Madison County Fair Market Rent is reported at $630 for a studio, $708 for one bedroom, $930 for two, and $1,227 for three. Voucher tenancy is a viable strategy in this market and worth understanding.
- No Rent Control: Nebraska has no statewide rent control and Norfolk has not adopted one. Nebraska Revised Statute 76-1490 requires at least sixty days written notice of a rent increase.
- No Just Cause Requirement: A landlord may decline to renew an expiring lease, and may terminate a month-to-month tenancy with at least 30 days written notice under Nebraska Revised Statute 76-1437(2).
- Security Deposits: Capped at one month’s rent, plus up to an additional one quarter month as a pet deposit. Return within 14 days with an itemized statement, or face liability of 1.5 times any amount wrongfully withheld.
- Nonpayment Notice: 3 day written notice to pay or vacate under Nebraska Revised Statute 76-1431(2). Lease violations generally get 14 days to cure with termination in 30.
Compliance Best Practices
Regulation is light here. Distance management and verification are where the real discipline lies:
- Verify Zoning and Occupancy Before You Offer: The small multi-family strategy depends entirely on the parcel legally supporting the unit count you are underwriting. Get it in writing during your inspection period.
- Watch for Unpermitted Conversions: Older Nebraska housing stock frequently contains units added without permits. That becomes your problem at closing and can affect financing and insurance as well as legality.
- Pull a FEMA Determination: Norfolk sits at a two-river junction. The determination costs under $150 and is cheap insurance against an expensive surprise, particularly on south-side and river-adjacent parcels.
- Hire Professional Management: At roughly 100 miles from Omaha, self-managing is impractical for most out-of-area owners. Budget the 7% to 9% and treat it as a fixed cost rather than an optional one.
- Separate the Utilities Where You Can: Older Norfolk multi-family often has one meter and one furnace serving multiple units. Separating them improves NOI permanently and makes the property far easier to sell in a thin resale market.
- Understand the Voucher Program: With Madison County FMR at $1,227 for a three bedroom, the Norfolk Housing Agency’s programs represent a real and reliable tenant pool worth evaluating.
- Protest the Assessment: Madison County assesses annually as of January 1. Protests go to the County Board of Equalization with appeal to the Nebraska Tax Equalization and Review Commission.
Useful Norfolk Resources
- City of Norfolk, for zoning, permits, occupancy, and building questions
- Norfolk Development Division and Norfolk Housing Agency, for voucher program information
- Madison County Assessor and Madison County Treasurer
- Madison County Register of Deeds, for recorded documents
- FEMA Flood Map Service Center, for parcel-level flood determination
- Nebraska Revised Statutes 76-1401 to 76-1449 (NURLTA)
| Regulation | Norfolk Situation | Nebraska State Law | Investor Impact |
|---|---|---|---|
| Zoning / Unit Count | Governs whether multi-family is permitted on a parcel | No statewide preemption | Decides whether the highest-return strategy here is available to you |
| Occupancy | Local rules govern unrelated occupants per dwelling | No statewide occupancy cap | Relevant to any by-the-room plan near the community college |
| Floodplain | City sits at the Elkhorn and North Fork junction | Federal NFIP rules plus local floodplain ordinances | Pull a determination on river-adjacent parcels before offering |
| Housing Vouchers | Norfolk Housing Agency administers local programs | Federal HUD program rules apply | Madison County FMR of $1,227 for a 3BR makes vouchers a viable tenant pool |
| Eviction | No local just cause ordinance | 3 day notice for nonpayment, 14/30 for lease breach | Among the faster eviction processes in the country |
| Property Tax | Madison County. This guide models 1.65% as a working figure. | State median near 1.39%, assessed at or near full market value | Well below Douglas County’s roughly 2.11%. Verify the parcel record. |
6. Step-by-Step Norfolk Investment Playbook
Define Your Norfolk Strategy
Four approaches work here, and all of them assume a long hold given the market’s remoteness:
Small Multi-Family Cash Flow
Buy a fourplex or duplex in the downtown core or Northern Heights, renovate to a durable standard, and hold. The fourplex example here produces $601 per month positive at a 7.47% cap rate, the strongest figures in this series.
Mid-Term Healthcare Rental
Furnish a unit near Faith Regional Health and lease on thirty day or longer terms to traveling clinicians. Premium rents in a market where standard rents are low, producing the highest cash-on-cash returns available here.
Value-Add Workforce Single-Family
Buy older stock well below the median and renovate for industrial and healthcare workers. Reaches roughly break even at 25% down, turns positive self-managed, and creates $30,000 to $50,000 of equity on a well-executed renovation.
House Hack Entry
Buy an owner-occupied duplex using FHA financing at 3.5 percent down, live in one unit, rent the other. At Norfolk duplex pricing this is the lowest-capital entry into real estate of any market in this series.
Build Your Norfolk Team
The professional bench here is the thinnest of any market in this series, which makes each hire matter more, not less.
- Property Manager, Hired First: In most markets this is a later decision. At 100 miles from Omaha it is the decision the entire investment rests on. Interview managers before you look at properties, and ask what they currently manage and what their vacancy has run.
- Investor-Focused Local Agent: Someone who knows which older properties are legally multi-family and hears about fourplexes before they list. With roughly 26 county sales a month, relationships are the deal flow.
- Nebraska Real Estate Attorney: For entity structure, NURLTA-compliant leases, and zoning questions on any conversion.
- General Contractor with Older-Home Experience: Knob-and-tube rewiring, galvanized repipes, sewer laterals, and utility separation are the recurring scopes. Vet carefully, since the contractor bench is thin.
- Real Estate CPA: For depreciation strategy and entity structuring across a small multi-family portfolio.
- Insurance Agent: Nebraska hail exposure drives premiums, and multi-family pricing differs from single-family.
Expert Tip: In Norfolk, hire the property manager before you buy anything. Ask one question: “What was your average days-to-fill on a two bedroom last year?” If they cannot answer with a number, keep looking. At this distance you are not managing a property, you are managing a manager, and the quality of that one relationship determines whether a 7.47 percent cap rate ever reaches your bank account.
Norfolk-Specific Due Diligence
Standard due diligence plus the items that specifically bite in this market:
Physical Due Diligence
- Sewer lateral scope on every older property, since most affordable stock is genuinely old
- Radon test, given Nebraska’s high radon zone status
- Utility metering, specifically whether units are separately metered for gas, electric, and water
- Heating configuration, since one furnace serving multiple units is common and expensive to fix
- Electrical service capacity and knob-and-tube presence in pre-1950 buildings
- Roof condition and hail claim history, which drives Nebraska insurance pricing
- Egress windows in every bedroom you intend to rent, including basement rooms
Regulatory and Financial Due Diligence
- Confirm zoning and permitted unit count in writing with the city
- Verify any existing multi-unit use is legal rather than an unpermitted conversion
- Obtain a written occupancy determination if you intend to lease by the room
- Pull a FEMA flood determination, particularly on south-side and river-adjacent parcels
- Run the Madison County parcel record for the actual tax figure, not a county average
- Verify actual rents against bank deposits rather than a stated rent roll
- Insist on closed comparable sales for the specific block, since county medians are meaningless here
Acquire, Lease, and Operate
Madison County homes have sold after roughly 37 days on about 26 monthly transactions, with new listings sometimes sitting 72 days. That slower pace gives a prepared buyer real room for diligence, and it also tells you what your eventual exit will look like.
Winning Offers in Norfolk
- Source off-market. With roughly 26 county sales a month and as few as two multi-family listings at a time, the MLS will not supply enough deal flow. Build the agent relationship and mail long-term owners from assessor records.
- Demand block-level comps. County medians have swung 25% and 57% in single months. Any offer priced off a citywide or county figure is priced off noise.
- Verify rents against deposits. On occupied multi-family, ask for bank statements. Below-market legacy rents are common and are also an opportunity.
- Underwrite utility separation. If units share meters, price the separation into your renovation. It permanently improves NOI and matters more for resale in a thin market.
- Use the slow pace. Properties sitting 37 to 72 days means you can complete proper diligence without losing the deal. Use that rather than rushing.
The Norfolk Leasing Calendar
- Workforce units lease year round. Industrial and healthcare employers hire on their own schedules, which makes Norfolk far less seasonal than a university market.
- March to July: Strongest general leasing window, as in most Nebraska markets.
- Properties near the college follow a partial August cycle, though a community college draws more commuting students than a residential campus.
- Late fall and winter: Slower for family units, though workforce demand holds up better here than in most small markets.
- Mid-term healthcare placements run on roughly thirteen week contracts independent of season, which smooths a mixed portfolio considerably.
Typical Norfolk Management Fees
- Single-family management: 8-10% of monthly rent
- Small multi-family management: 7-9% of monthly rent
- Furnished mid-term management: 10-15%, reflecting higher turnover and coordination
- Leasing fee: 50-100% of one month’s rent
- Lease renewal fee: $150-$250 per renewal
7. Financing Options for Norfolk
| Loan Type | Down Payment | Rate Premium | Best For | Norfolk Note |
|---|---|---|---|---|
| DSCR Loan | 20-25% | +1.0-2.0% | Investors avoiding income verification | The strongest DSCR market in this series. A fourplex reaches about 1.42x. |
| Conventional Investment | 20-25% | +0.5-0.75% | W-2 income, good credit, 1-4 unit purchases | $71,250 down on a $285,000 fourplex producing $601 per month positive |
| House Hacking (FHA) | 3.5% | Standard + MIP | Owner-occupying one unit of a 2-4 unit property | Roughly $6,800 down on a $195,000 duplex. The lowest entry in this series. |
| Local Portfolio Loan | 20-30% | +0.75-1.75% | Multiple properties, self-employed, blanket loans | Northeast Nebraska community banks know this market far better than national lenders |
| 203(k) / Renovation Loan | 3.5-25% | +0.25-1.0% | Buying and renovating in one loan | Excellent fit, since nearly all worthwhile multi-family here needs work |
| Commercial / Small Balance | 25-30% | +1-2% | Five or more units | Above four units you lose residential financing. Stay at four where you can. |
| Appraisal Risk (Any Loan) | Varies | Varies | All Norfolk purchases | With ~26 county sales a month, multi-family appraisals can come in low or slow. Build timeline buffer. |
Norfolk Financing Reality: This is the strongest DSCR market in the series. The sample fourplex produces roughly $2,023 of monthly NOI against a $1,422 payment, about 1.42x coverage, ahead of Fremont’s 1.36x, Kearney’s 1.34x, and Grand Island’s 1.23x. A Norfolk duplex reaches about 1.27x, and even a value-add single-family reaches roughly 0.97x, essentially neutral. The offsetting issue is appraisal. With roughly 26 county sales a month and recent transactions ranging from $152,630 to $800,000, an appraiser has genuinely thin comparable data to work from, especially on multi-family. Build extra time into your financing contingency and be prepared for a value that surprises you in either direction.
8. Frequently Asked Questions

Knowledge Quiz: Norfolk Real Estate Investment
Open Quiz
5 quick questions on what you just learned about Norfolk investing
1) What returns does a renovated Norfolk fourplex produce?
Answer: C
A $285,000 purchase plus $40,000 renovation grossing $3,500 produces about $2,023 of monthly NOI against a $1,422 payment. That beats Kearney’s 7.27% and $576, Fremont’s 7.21% and $546, and Grand Island’s 6.74% and $375.
2) What is the main drawback of investing in Norfolk?
Answer: B
Every Norfolk drawback traces to distance or thin volume: impractical self-management, no reliable citywide comps, a thin resale market, a small professional bench, and difficult multi-family appraisals. The high cap rate is compensation for exactly those things.
3) Who should you hire first when investing in Norfolk?
Answer: A
At roughly 100 miles from Omaha, you are not managing a property, you are managing a manager. Ask what their average days-to-fill was on a two bedroom last year. If they cannot answer with a number, keep looking. That one relationship determines whether the cap rate ever reaches your account.
4) Why are Norfolk price reports unreliable?
Answer: D
County medians printed up 57.4% in one month and up 25.8% in another. Reported figures span a home value near $211,700, a closing median near $240,000, a county median near $276,727, and a monthly print of $315,000. County data also blends in Madison, Battle Creek, and Tilden. Only block-level closed comps are usable.
5) How does Norfolk compare to Fremont for a cash flow investor?
Answer: B
Norfolk reaches a 7.47% cap with $601 positive against Fremont’s 7.21% and $546. Fremont delivers roughly 91% of the cash flow at about a third of the driving distance. If you plan to be hands-on, Fremont. If you are hiring management either way and purely optimizing returns, Norfolk.
Work With a Local Expert in Norfolk
We are building a verified network of real estate professionals across every market we cover.

About Our Expert Network
We are finalizing partnerships with verified real estate professionals across every market featured on Builds and Buys. Each expert in our network is selected for their hands-on investment experience, local market knowledge, and commitment to helping buyers and investors make sound decisions.
Our local specialists offer:
- Proven experience with investment and income-producing properties
- Deep knowledge of local pricing, rental yields, and neighborhood dynamics
- Guidance on financing, legal structure, and due diligence
- Access to off-market and pre-market opportunities
- Full transaction support from search through closing
- Ongoing portfolio and property management referrals
Services Covered
- Property sourcing and acquisition
- Investment analysis and underwriting
- Buyer representation
- Market comparables and valuations
- Short-term and long-term rental strategy
- Value-add and renovation guidance
- Legal and title referrals
- Financing and lender connections
- Property management referrals
- Insurance and inspection referrals
- 1031 exchange coordination
- Exit strategy planning
Get Connected or Join Our Network
Looking for a local expert to help with your investment? Reach out and we will connect you with the right professional for your market and strategy.
Are you a real estate professional with a track record working with investors? We are always expanding our network of verified local experts.
Contact us at support@buildsandbuys.com
Find Specialized Norfolk Real Estate Professionals
Ready to Invest in Norfolk?
Norfolk produces the strongest returns of any market in our Nebraska series. A renovated fourplex delivers roughly $601 per month positive at a 7.47 percent cap rate and clears debt service at about 1.42x, ahead of Kearney, Fremont, and Grand Island. Behind those numbers sits a steel and metals manufacturing base, a regional hospital serving a wide catchment, a community college, and status as northeast Nebraska’s retail hub. The cost of those returns is distance and thinness: roughly 100 miles from Omaha, about 26 county sales a month, no reliable citywide comps, and a thin resale market. Hire the property manager before you buy anything, price off block-level closed sales only, keep deeper reserves than you would in a metro, and plan to own it for a decade. Do that and Norfolk pays better than anywhere else in Nebraska.
Continue Your Research
For further guidance, explore our State-by-State Investor guides, browse our expert articles, or follow our Step-by-Step Investment Guide.