Mountain Home Idaho Real Estate Investment Guide For 2026
A comprehensive resource for investors targeting one of Idaho’s most stable military housing markets, with BAH-backed rental income, affordable entry prices, and consistent demand from Mountain Home Air Force Base
Quick answers: Top 5 most searched Mountain Home investment questions ▼
Migration data: Who’s renting in Mountain Home and why ▼
1. Mountain Home Market Overview
Market Fundamentals
Mountain Home is a city of approximately 14,000 to 15,000 residents in Elmore County, located 45 miles southeast of Boise along the I-84 corridor. It is defined almost entirely by its relationship with Mountain Home Air Force Base, home of the 366th Fighter Wing, one of the Air Force’s premier composite wing installations flying F-15 Eagles. The base employs 3,500 to 4,000 active duty service members plus approximately 1,500 civilian employees and contractors. That population anchors Mountain Home’s real estate market in a way that no private employer could, because military demand is funded directly by the federal government regardless of local or national economic conditions.
Key market fundamentals:
- Primary Demand Driver: Mountain Home AFB, 366th Fighter Wing, F-15 Eagles
- Active Duty Population: 3,500-4,000 with approximately 60% living off-base
- Civilian/Contractor Workforce: 1,500+ additional base employees
- Median Home Price: $295,000 (well below any Boise Metro community)
- Typical 3BR Rent: $1,350-$1,650 (BAH-indexed)
- Vacancy Rate: 5-8% (higher than Boise Metro; deployment cycles create periodic vacancies)
- Boise Commute: 45 miles on I-84, approximately 45 to 55 minutes
Mountain Home’s investment appeal is fundamentally different from every other Idaho city. It is not a growth story, an appreciation story, or a cash flow maximization story in the conventional sense. It is a stability story. Military housing markets generate predictable, federally-backed rental demand that persists through recessions, rate cycles, and local economic disruptions. The trade-off is that the market’s upside is also constrained: rents track BAH rates, appreciation tracks national military community averages, and the local economy has limited diversification beyond the base.
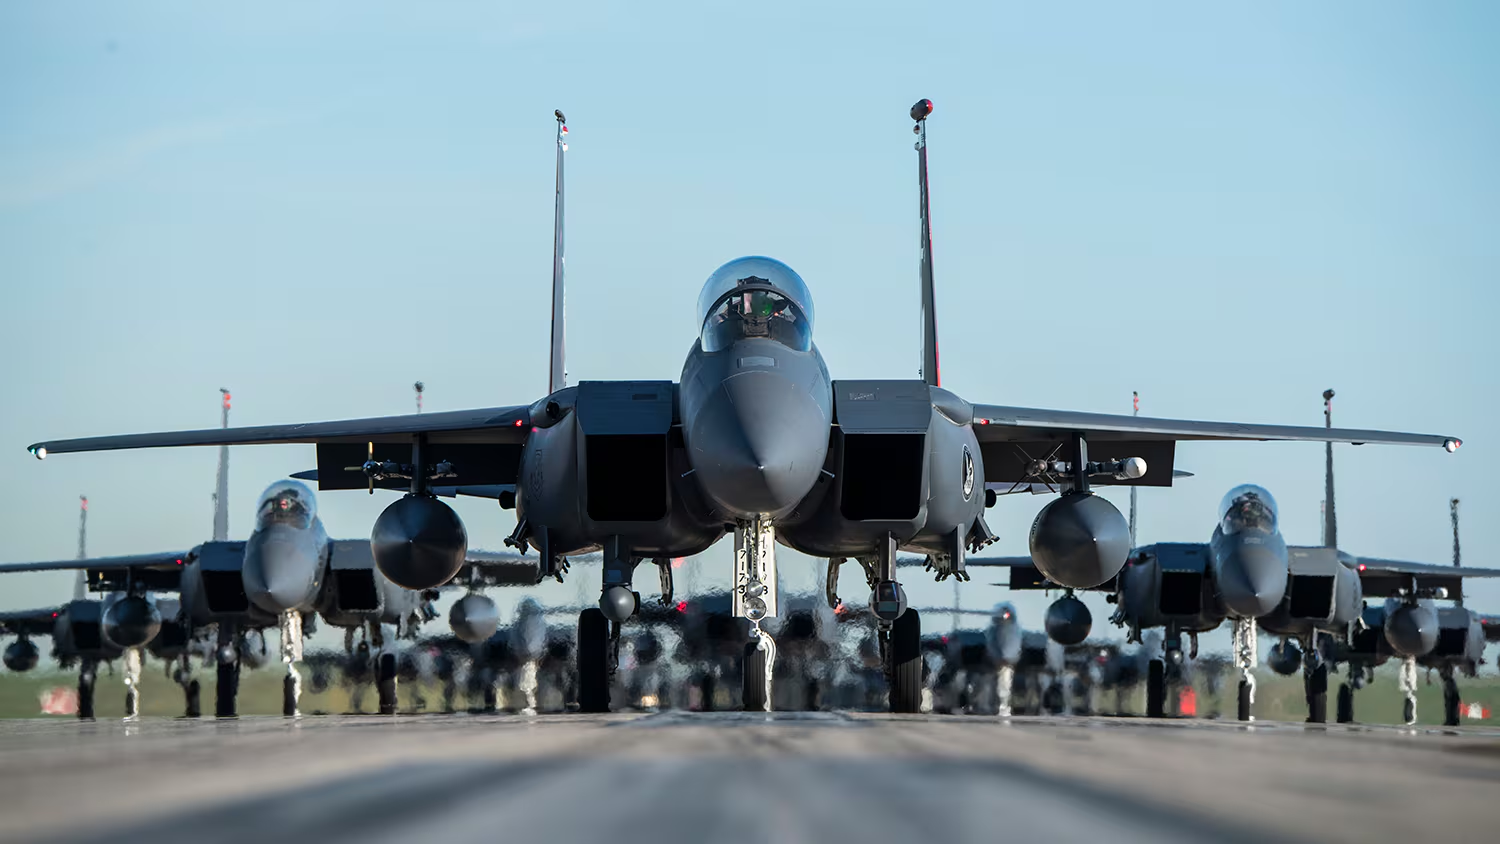
Mountain Home AFB’s 366th Fighter Wing anchors a rental market that is uniquely insulated from local economic cycles
Mountain Home AFB: Key Facts
- Unit: 366th Fighter Wing, 12th Air Force
- Aircraft: F-15C/D Eagles (air superiority)
- Mission: Composite wing: air superiority, strike, support
- History: One of the Air Force’s most decorated fighter wings
- On-base housing: Managed by Hunt Companies (privatized)
- Strategic importance: Pacific and global rapid deployment capable
Understanding BAH: The Engine of Mountain Home’s Rental Market
Basic Allowance for Housing is the single most important concept for Mountain Home investors to understand. BAH is a non-taxable monthly payment made to service members who do not live in government-provided housing, calculated to cover rental costs at the 95th percentile of local market rents. It is adjusted annually based on local housing surveys.
| Pay Grade | Rank Example | BAH Without Dependents | BAH With Dependents | Landlord Implication |
|---|---|---|---|---|
| E-4 | Senior Airman | ~$1,050-$1,200 | ~$1,300-$1,450 | Targets 1-2BR units or roommate arrangements |
| E-5 | Staff Sergeant | ~$1,150-$1,300 | ~$1,400-$1,600 | Primary 3BR SFH tenant segment; most common in the market |
| E-6/E-7 | Tech / Master Sergeant | ~$1,250-$1,400 | ~$1,550-$1,750 | Can afford quality 3BR-4BR; longest typical tours at Mountain Home |
| O-3 | Captain | ~$1,400-$1,600 | ~$1,750-$2,050 | Officers target newer or updated 3-4BR; willing to pay above E-rate for quality |
| O-4/O-5 | Major / Lieutenant Colonel | ~$1,550-$1,750 | ~$1,950-$2,200 | Best-quality tenants; target 4BR updated homes; will pay Mountain Home’s premium tier |
These are approximate BAH rates for the Mountain Home/Elmore County area as of 2026 and are subject to annual adjustment. The core insight: if your property’s rent aligns with the BAH rate for the predominant pay grade living off-base at MHAFB, you have access to a tenant pool whose housing payment is guaranteed by the U.S. government. That is a fundamentally different risk profile from civilian rental markets.
Mountain Home vs. Idaho’s Other Investment Markets
| Market | Demand Driver | Median Price | Yield | Primary Risk |
|---|---|---|---|---|
| Mountain Home | Federal military (MHAFB) | $295K | 6-7% | Base closure / SCRA lease breaks |
| Rexburg | BYU-Idaho (LDS institution) | $320K | 7-10% | Enrollment decline / summer vacancy |
| Caldwell | Boise Metro overflow, manufacturing | $355K | 5.5-7% | Economic cycle sensitivity |
| Kuna | Boise Metro appreciation play | $390K | 4.5-5.5% | Negative cash flow; HOA caps |
📚 New to real estate investing? Master the fundamentals with our professional 144-lesson course Learn more →
2. Neighborhood Hotspots
Mountain Home Investment Neighborhood Map
Interactive map of Mountain Home’s investment neighborhoods relative to MHAFB. Green stars show top hotspots, blue circles mark established markets, and orange circles highlight emerging areas.
Core Investment Neighborhoods
Detailed Submarket Analysis
| Neighborhood | Distance to Gate | Price Range | Cap Rate | Best Strategy |
|---|---|---|---|---|
| Base-Adjacent / Airbase Rd | 1-3 miles | $235K-$320K | 6-8% | Buy-and-hold, multi-family priority |
| NE Mountain Home / Newer | 3-6 miles | $270K-$370K | 5.5-7% | Passive hold, officer/senior NCO targeting |
| Central / American Legion Blvd | 2-5 miles | $240K-$330K | 6-7.5% | Balanced hold, duplex opportunities |
| NW Mountain Home / Residential | 3-6 miles | $255K-$345K | 5.5-7% | Passive family hold, low management |
| East Mountain Home / Value-Add | 3-6 miles | $220K-$300K | 6.5-8% | Value-add, BRRRR, highest yield entry |
| South / I-84 Corridor | 4-7 miles | $240K-$330K | 5.5-7% | Dual military/commuter demand |
Expert Insight: “Distance to the MHAFB main gate is the single most important variable in Mountain Home real estate. A property two miles from the gate and a property eight miles from the gate are in fundamentally different rental markets. Military families, especially with children, prioritize the gate commute above almost everything else. I have watched $50,000 price gaps between comparable properties evaporate quickly when the cheaper one is just a mile or two closer to base. Investors who do not understand this dynamic systematically over-pay for remote Mountain Home properties and under-appreciate base-adjacent ones.” – Marcus Webb, Elmore County Military Housing Specialists
3. Property Types
3-Bedroom SFH (Core Military Family Product)
The dominant Mountain Home rental product. Three-bedroom homes targeting E-4 through E-6 families represent the largest tenant segment. Properties in the $240,000 to $300,000 range with functional layouts and decent condition lease quickly to military families. Not glamorous but consistent.
4-Bedroom SFH (Officer and Senior NCO Market)
Updated or newer 4-bedroom homes in northeast Mountain Home target the officer corps and senior NCOs (E-7+) who receive higher BAH rates and have higher housing expectations. This segment delivers the best Mountain Home rents ($1,650-$1,900 per month) with the lowest property damage and longest average tenure.
Duplexes (Best Cash Flow Vehicle)
Small multi-family in Mountain Home offers the best path to break-even or positive cash flow. A duplex with two 2BR units renting at $1,100 to $1,250 per side generates $2,200 to $2,500 monthly gross income. At $320,000 to $360,000 purchase prices, the numbers approach neutral carry at current rates. Best option for income-focused investors.
Value-Add SFH
Older homes in east Mountain Home and the central corridor from the 1970s through 1990s that need updating. Purchase prices of $220,000 to $265,000 make renovation math accessible. A kitchen and bath refresh, new flooring, and paint can push rents above the base-adjacent average and attract quality military tenants willing to pay for better condition.
DoD Contractor / Mid-Term Furnished
Base contractors frequently rotate in and out on 30 to 180 day temporary duty assignments. Furnished 3BR homes near the base renting at $2,000 to $2,800 per month for 30+ day stays can materially improve Mountain Home cash flow. No STR restrictions in Mountain Home as of 2026. Requires more active management but income premium offsets negative carry.
Rural Residential / Elmore County Acreage
Larger parcels beyond Mountain Home city limits at prices per acre impossible in any Boise Metro community. Appeals to military families with horses, large families seeking space, and hunters/outdoor recreation enthusiasts. Lower yields but high tenant loyalty from lifestyle-matched renters who stay until their PCS orders arrive.
Get accurate cost estimates before you commit. Our Complete Renovation & Remodeling Cost Guide covers 400+ project types with real contractor pricing.
4. Cost Analysis
Acquisition Cost Breakdown (Mountain Home)
| Expense Item | Typical Cost | Example ($295,000 Property) | Notes |
|---|---|---|---|
| Down Payment | 25% (investment) | $73,750 | Some active duty investors use VA loans with 0% down if owner-occupying initially |
| Closing Costs | 2-3% | $5,900-$8,850 | Elmore County title and escrow costs are modest |
| Inspection | $300-$450 | $375 | Pay attention to HVAC; Mountain Home has extreme summer heat and cold winters |
| SCRA Reserve Fund | 2 months rent | $3,000-$3,500 | Dedicated reserve for re-leasing costs after SCRA terminations |
| Operating Reserves | 6 months PITI | $10,000-$13,000 | Important given potential SCRA vacancies and seasonal deployment cycles |
| TOTAL MINIMUM ENTRY | ~32-36% | $93,000-$115,000 | Among the lowest absolute capital requirements of any Idaho investment market |
Sample Cash Flow Analysis: Duplex Near MHAFB Main Gate
| Item | Monthly | Annual | Notes |
|---|---|---|---|
| Unit 1 Rent (2BR) | $1,200 | $14,400 | E-4/E-5 military family, base-adjacent duplex |
| Unit 2 Rent (2BR) | $1,175 | $14,100 | Slightly smaller or different exposure |
| Gross Income | $2,375 | $28,500 | |
| Less Vacancy (8%) | -$190 | -$2,280 | Higher than Boise Metro; accounts for SCRA deployment-related vacancies |
| Property Taxes | -$155 | -$1,860 | Elmore County ~0.65% of $287K assessed value |
| Insurance | -$105 | -$1,260 | Landlord policy on duplex |
| Property Management (10%) | -$219 | -$2,622 | PM with military housing/SCRA experience preferred |
| Maintenance + CapEx (8%) | -$174 | -$2,088 | Older duplex stock; budget 8% |
| Net Operating Income | $1,532 | $18,390 | Before mortgage |
| Mortgage ($345K, 25% down, 6.75%, 30yr) | -$1,677 | -$20,124 | $258,750 loan at 6.75% |
| CASH FLOW | -$145 | -$1,734 | Near break-even; best Mountain Home cash flow scenario |
| Cap Rate | 5.33% | NOI / Purchase Price | |
| Total Return (6% appreciation) | ~17% | Equity + appreciation on leveraged basis, net of cash flow cost |
Near break-even on a duplex near MHAFB is a strong result for the current rate environment and represents a better entry position than Kuna or any Boise suburb. The stability advantage is significant: the $1,532 monthly NOI is backed by BAH payments from the federal government, not discretionary civilian income. In a recession, the BAH-funded Mountain Home duplex performs more consistently than a comparable civilian rental in Boise or Nampa. For a 3BR SFH comparison: a $265,000 property with $1,500 rent runs approximately -$280 to -$350/month after all expenses, which is the honest picture for single-family military housing at current rates.
VA Loan Strategy for Active Duty Investors: Active duty service members purchasing investment property can use a powerful sequencing strategy. Buy a Mountain Home property as a primary residence using a VA loan (0% down, no PMI, below-market rates). After receiving new PCS orders, convert to a rental under their existing VA entitlement. This allows entry at $0 down versus the $73,750+ required for conventional investment financing. The cash flow picture on VA-financed properties is significantly better due to lower loan amounts and rates. This strategy is one reason some of the savviest Mountain Home investors are the service members themselves.
5. Legal Framework
✅ Idaho State Law: Fully Landlord-Friendly
Elmore County and the City of Mountain Home follow Idaho Code Title 55 statewide law with zero additional local landlord regulations. No rent control, no just cause eviction, no source of income protection, no rental registration. This is the same favorable legal environment as every other Idaho city. The unique legal dimension in Mountain Home is not from state or local law but from federal law: the Servicemembers Civil Relief Act.
⚠️ Federal Law Alert: Servicemembers Civil Relief Act (SCRA)
The SCRA is a federal statute (50 U.S.C. §§ 3901–4043) that grants specific legal protections to active duty military personnel. The most significant provision for Mountain Home landlords is the right to terminate a residential lease early. Understanding the SCRA is non-negotiable for any investor operating in a military community.
When Military Tenants Can Break Your Lease
- Receipt of Permanent Change of Station (PCS) orders requiring a move of 35+ miles
- Deployment orders for 90 or more days
- Separation or retirement from military service
- Entry onto active duty (National Guard or Reserve members)
How SCRA Termination Works
- Tenant provides written notice plus a copy of their military orders
- Termination is effective 30 days after the next scheduled rent payment date
- Landlord cannot charge early termination fees or withhold deposit for SCRA exits
- Lease termination is complete and the tenant has no further payment obligation
- Landlord’s remedies: none against the service member for the SCRA termination itself
Managing SCRA Risk Effectively
SCRA is not a dealbreaker for Mountain Home investing; it is a manageable operational reality that experienced military housing landlords build into their business model:
- Price in Re-Leasing Costs: Budget 8 to 10% annual vacancy versus the 4 to 5% you might use in a civilian market. The extra 3 to 5% accounts for SCRA terminations and deployment-related gaps.
- Maintain a Re-Leasing Pipeline: The base housing Facebook groups, military spouse networks, and word-of-mouth recommendations are the primary channels where Mountain Home military tenants find rentals. Join or advertise in these communities before a vacancy opens.
- Welcome SCRA Terminations: Each SCRA termination is an opportunity to re-let at updated market rates. In a rising rent environment (which tracks BAH increases), a tenant who was locked into a 2-year-old rate creates value when they leave on SCRA grounds.
- Target DoD Civilians and Contractors: These individuals are not subject to SCRA. A deliberate strategy to prefer DoD civilian tenants reduces SCRA exposure while maintaining the federally-connected income stability.
- Lease Addendum: Use a lease addendum that confirms the tenant’s understanding of SCRA notification requirements and documents their military status at signing. This protects you from confusion during the termination process.
Idaho Law Advantages for Military Landlords
- Fast Eviction for Non-SCRA Issues: When military tenants breach their lease for reasons unrelated to SCRA (damage, unauthorized guests, drug activity), Idaho’s 3-day notice and 3 to 4 week eviction process applies. Unlike SCRA, which is a federal protection, non-SCRA lease violations follow standard Idaho unlawful detainer procedures.
- No Just Cause Requirement: At lease expiration, landlords can decline to renew any tenant’s lease without explanation. This gives Mountain Home landlords full flexibility to transition from one military family to another as PCS cycles dictate.
- No Rent Control: BAH rates increase annually based on local housing surveys. As BAH rises, landlords can immediately adjust rents at renewal, unlike rent-controlled markets where increases are capped regardless of the military’s own housing surveys.
- Security Deposit: No statutory cap. Standard military housing practice is to collect first month plus a security deposit equal to one month’s rent.
- No Rental Registration: No permits, inspections, or compliance reporting required in Mountain Home or Elmore County beyond standard Idaho law.
| Legal Issue | Governing Law | Mountain Home Outcome | Investor Action |
|---|---|---|---|
| Lease Early Termination (PCS/Deployment) | Federal SCRA | Tenant can terminate with 30 days notice + orders | Budget 8-10% vacancy; maintain re-leasing pipeline |
| Non-Payment Eviction | Idaho Code Title 55 | 3-day notice, 21-35 day process | Same fast Idaho process applies to military and civilian alike |
| Rent Increases | Idaho state law (no control) | Landlord can raise at renewal to match BAH increases | Review BAH tables annually; adjust rents at each renewal |
| Lease Non-Renewal | Idaho state law | 30-day notice, no reason required | Use to remove problem tenants or reposition for better tenant |
| Interest Rate Protection | Federal SCRA | SCRA caps interest rates at 6% on pre-service debts (not applicable to landlords) | Applies to tenant loans, not your rent; no direct impact |
6. Step-by-Step Mountain Home Investment Playbook
Define Your Mountain Home Strategy
Military Family SFH
3 to 4BR homes targeting E-5 through O-3 military families. Core Mountain Home strategy. BAH-funded rent, consistent demand, near-stable carry. Target gate-adjacent or northeast Mountain Home for best results.
Duplex / Small Multi-Family
Best cash flow vehicle in Mountain Home. Two BAH-funded income streams reduce SCRA risk (unlikely both units vacate simultaneously). Near break-even possible at current prices and rates.
DoD Civilian / Contractor Targeting
Deliberately seek DoD civilian and contractor tenants over active duty. Longer tenure, no SCRA exposure, similar BAH-level income from government employment. Requires patience to find the right tenant but reduces operational complexity significantly.
Mid-Term Furnished / Contractor Rotation
Furnish a property near the base entrance and market to TDY (Temporary Duty) contractors and personnel on 30 to 180 day assignments. Premium rents of $2,000 to $2,800 per month can push Mountain Home cash flow positive. Active management required.
Build Your Mountain Home Team
- Agent with MHAFB Transaction Experience: Must understand military PCS cycles, SCRA implications on deal timing, and which neighborhoods active duty families specifically request. Ask how many military buyer and seller transactions they have closed at Mountain Home in the last 12 months.
- Property Manager with Military Housing Experience: Essential for SCRA management, military community networking for re-leasing, and understanding of base housing office procedures. A PM who has never managed military housing will be unprepared for SCRA notifications and the specific tenant communication style expected in military communities.
- Elmore County Contractor: Mountain Home’s smaller market means fewer contractors. Build relationships before you need them. Good contractors in the area are often booked months out; having existing relationships keeps your vacancy windows short.
- Idaho CPA: Same requirements as other Idaho markets. Depreciation strategy and any VA loan conversion considerations are worth professional guidance.
Mountain Home-Specific Due Diligence
Location Verification
- Physically drive from the property to MHAFB main gate and time the commute
- Verify school district and specific school assignment
- Check proximity to base grocery (Commissary), gas station (AAFES), and other on-base services that military families use daily
- Note flight patterns: F-15 operations are loud; properties under approach patterns have lower demand from families with young children
Physical and Market Checks
- HVAC inspection is critical: Mountain Home summers exceed 100°F and winters are harsh; a failing AC or furnace creates immediate tenant crises
- Verify current BAH rates for your target pay grade at MHAFB before setting asking rent
- Elmore County Assessor: verify actual tax amounts; Elmore County has modest but non-trivial property taxes
- Check current on-base privatized housing waitlist status: when Hunt Military Communities housing has a waitlist, off-base demand is highest
Operate Successfully in the Military Housing Market
Marketing to Military Tenants
- Military Housing Facebook Groups: Post in Mountain Home AFB and “366th Fighter Wing Spouses” Facebook groups 60 days before any anticipated vacancy. Military families research housing before receiving orders.
- MHAFB Housing Office: Register your property with the base housing referral office if they maintain an off-base listing service. Some bases actively refer families to approved off-base properties.
- BAH-Aligned Pricing: Price at or slightly below the BAH for your target pay grade. Service members strongly prefer rentals within their BAH because any excess comes directly out of pay. Being $50 to $100 per month under BAH dramatically increases your applicant pool.
- Pet Policy: Military families often have pets. A pet-friendly policy (with appropriate deposits) significantly expands your eligible tenant pool. Many military families specifically search for pet-friendly rentals and will pay a premium.
- PCS-Friendly Lease Structure: Offer lease terms that align with typical PCS cycles (12 or 24 months) with a specific SCRA clause. Families appreciate transparency about the SCRA process.
7. Financing Options for Mountain Home
| Loan Type | Down Payment | Rate | Best For | Mountain Home Note |
|---|---|---|---|---|
| VA Loan (Primary Residence) | 0% | Below market, no PMI | Active duty investors buying primary residence first | Most powerful Mountain Home tool. Buy as primary, receive PCS orders, convert to rental. Access to 0% down and below-market rates impossible with investment financing. |
| Conventional Investment | 25% | +0.5-0.75% | Civilian investors, standard investment purchase | All Mountain Home properties within conforming limits. Standard approach for most investors. |
| DSCR Loan | 20-25% | +1.5-2.5% | Self-employed; duplex investors | Mountain Home duplexes at good prices can qualify at 1.0x DSCR given better yields than metro markets. Verify with signed BAH-level lease estimates. |
| FHA (House Hack) | 3.5% | Standard + MIP | First-time investors willing to owner-occupy a duplex unit | Mountain Home duplex house hack: owner-occupy one unit, rent other to military family. 3.5% down on a $340K duplex = $11,900, with the rented unit covering half the mortgage. |
| Hard Money / Bridge | 15-25% | 8-12% | Value-add projects in older Mountain Home stock | Use for fast close on distressed east Mountain Home properties; refinance to conventional post-renovation |
VA Loan Cascade Strategy (Active Duty Investors): The most advantageous Mountain Home strategy for active duty service members uses VA loan benefits sequentially. Buy Property 1 as a primary residence with VA loan (0% down) at Mountain Home. Live there for 12+ months. Receive PCS orders or choose to move. Convert Property 1 to rental. Buy Property 2 at the new duty station with another VA loan (VA entitlement can be restored or used simultaneously for second VA loan above certain thresholds). Repeat at each PCS. This strategy allows a service member to build a portfolio of rental properties with minimal down payment while maintaining access to below-market rates at each step. It is one of the most well-known wealth-building strategies in the military community and explains why some of Mountain Home’s most sophisticated landlords are veterans.
8. Frequently Asked Questions

Knowledge Quiz: Mountain Home Idaho Real Estate Investment
Open Quiz
5 quick questions on Mountain Home military housing investing
1) What is BAH and why is it important for Mountain Home landlords?
Answer: B
BAH is a non-taxable monthly housing allowance paid directly to service members who live off-base, calculated to cover rents at the 95th percentile of local housing costs. It is adjusted annually. For Mountain Home landlords, BAH creates a pricing floor: set your rent at or just below the BAH for your target pay grade and you access a tenant pool whose housing payment is backed by the U.S. government, regardless of local or national economic conditions.
2) Under the SCRA, under what circumstances can a military tenant break your lease?
Answer: C
The SCRA allows active duty service members to terminate residential leases with 30 days written notice and a copy of their military orders when: receiving PCS orders to move 35+ miles, receiving deployment orders for 90+ days, or separating from active duty. Landlords cannot charge early termination fees or withhold deposits for SCRA exits. The tenant has no further payment obligation after the SCRA termination date.
3) Which property type does the guide identify as the best cash flow option in Mountain Home?
Answer: A
The guide’s cash flow analysis shows a duplex purchased for $345,000 near the MHAFB main gate, with two 2BR units renting at $1,175 to $1,200 per month each, achieving approximately -$145/month cash flow, the closest to break-even of any Mountain Home scenario. Two BAH-funded income streams reduce SCRA risk because it is unlikely both units vacate simultaneously, and the per-unit income makes the numbers work better than any SFH at equivalent total investment.
4) What does the guide identify as the single most important location factor for Mountain Home investment properties?
Answer: D
The guide’s expert insight explicitly states that gate proximity is the single most important variable. Military families, especially those with children and two-career households, prioritize the base commute above almost everything else. Properties 2 miles from the gate and 8 miles from the gate are in fundamentally different rental markets. The expert noted watching $50,000 price gaps between comparable properties evaporate when the cheaper one was just a mile or two closer to base.
5) What is the VA Loan Cascade Strategy described in the guide?
Answer: B
The VA Loan Cascade is a well-known military wealth-building strategy. Service members buy their first home at each duty station as a primary residence using a VA loan with 0% down and below-market rates. When PCS orders arrive, they convert that property to a rental and buy again at the new duty station using VA entitlement (which can be restored or used concurrently above certain thresholds). Over a 20-year military career with 4 to 6 PCS moves, a disciplined service member can build a portfolio of 4 to 6 rental properties with minimal down payments.
Work With a Local Expert in Mountain Home
We are building a verified network of real estate professionals across every market we cover.

About Our Expert Network
Our Mountain Home specialists are selected specifically for their military housing experience. Each expert understands SCRA requirements, BAH rate dynamics, VA loan sequencing strategies, and the Mountain Home AFB community networks used to fill vacancies quickly after PCS moves.
- Proven experience managing SCRA lease terminations and rapid military re-leasing
- Access to base Facebook groups and housing office referral channels
- VA loan expertise for active duty investors using the cascade strategy
- Property management referrals with military housing track records
- Full transaction support including understanding of military PCS timelines
Get Connected or Join Our Network
Contact us at support@buildsandbuys.com
Find Mountain Home Real Estate Professionals
Ready to Invest in Mountain Home?
Mountain Home is one of the few Idaho markets that offers something no Boise suburb can match: federally-backed rental demand that does not fluctuate with the local or national economy. Military families pay rent from BAH regardless of whether tech companies are hiring in Boise or what interest rates are doing nationally. Idaho’s landlord-friendly laws make the SCRA an efficiently managed operational reality rather than a paralyzing risk. At median prices of $295,000 and duplex near-break-even cash flow, Mountain Home offers a stability and income combination that more expensive, more volatile markets simply cannot provide. For investors who value consistent, federally-secured income at affordable entry costs and are willing to understand the military housing market’s specific dynamics, Mountain Home deserves serious consideration in any Idaho portfolio.
Continue Your Research
Idaho State Guide
See how Mountain Home compares to every other Idaho market across the full state investment landscape.
Caldwell Guide
Compare Mountain Home’s stability play with Caldwell’s cash flow and revitalization story in Canyon County.
144-Lesson Course
University-level investment education covering military housing strategies, VA financing, and long-term portfolio building.
For further guidance, explore our State-by-State Investor guides, browse our expert articles, or follow our Step-by-Step Investment Guide.