Dallas Real Estate Investment Guide For 2026
A comprehensive resource for investors looking to capitalize on a genuinely functional cash flow market working through a builder-driven supply correction in 2026
Quick answers: Top 5 most searched Dallas investment questions ▼
Migration data: Where people are moving from to Dallas ▼
In This Guide
Click on any section to navigate directly to that content
1. Dallas Market Overview
Market Fundamentals
Dallas-Fort Worth enters 2026 as arguably the most textbook example of a supply-driven correction among major U.S. metros. From the walkable Bishop Arts District in Oak Cliff to the corporate campuses of the Telecom Corridor, DFW offers a genuinely diversified economy layered under a housing market that simply built too much, too fast, during the pandemic years.
Key economic indicators that define Dallas’s investment case:
- Population: 1.3M+ city proper, 8.1M+ greater metro area, one of the fastest-growing large metros in the country
- Major Employers: AT&T, American Airlines, Toyota North America, Goldman Sachs, Charles Schwab, JPMorgan Chase, Texas Instruments, Parkland Health
- Unemployment Rate: 3.6%, low by any national benchmark
- No State Income Tax: continues to draw corporate relocations and finance sector professionals
- Metro Median Sale Price: approximately $400,000-$415,000 depending on data source and month
- Months of Inventory: approximately 5.4-5.5, a genuine buyer’s market
Dallas’s economy is anchored by one of the most diversified corporate headquarters bases of any major U.S. metro, spanning financial services, technology, healthcare, logistics, and telecommunications. The current price correction is fundamentally a supply story: homebuilders built aggressively for a demand environment that has since moderated, not a market where jobs or population are leaving.
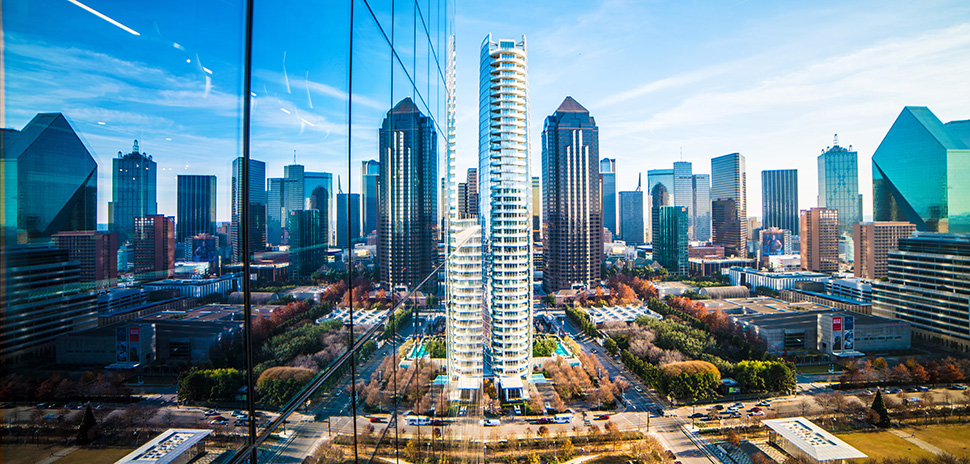
Dallas’s skyline reflects a genuinely diversified corporate economy working through a builder-driven supply correction
2026 Economic Outlook
- Sales volume up 7.47% year over year even as median prices moderate, per TRERC April 2026 data
- New apartment construction slowing after nearly 97,000 units delivered in 2024
- Continued corporate relocation activity from finance and technology sectors
- Outer suburb growth (Princeton, Celina, Anna, Melissa) absorbing the bulk of new supply
- M&D Real Estate projects DFW transaction volume up approximately 10% in 2026 as rates potentially ease
Investment Climate
Dallas’s investment environment in 2026 is defined by a genuinely favorable combination for cash flow investors: functional rental yields, intact employment fundamentals, and a builder-driven inventory surge that has handed buyers real negotiating leverage without signaling underlying economic weakness. Successful Dallas investors tend to share a few characteristics:
- ZIP code precision since the correction is highly uneven, closer-in neighborhoods with tighter supply constraints have held up materially better than outer suburbs flooded with new construction
- Cash flow orientation given that DFW’s roughly 5.4% gross yield is genuinely workable, unlike Austin or Seattle
- Property tax discipline since Dallas County carries the highest effective property tax burden of any major Texas metro
- Supply awareness avoiding outer-ring suburbs still absorbing the bulk of 2023-2025 construction unless buying at a genuine discount reflecting that oversupply
- Total return patience accepting a near-flat 12-month price outlook in exchange for durable rental income and long-term population growth exposure
The PropertyIQ Score placed DFW at 31 out of 100 as of February 2026, reflecting a supply-heavy market where 21% of listings carried price cuts. But the same analysis is explicit that the economic case for Dallas is real: the current supply-demand imbalance is a buyer-favorable pricing environment, not evidence of a deteriorating metro.
Historical Performance
| Period | Market Driver | Avg Annual Change | Key Event |
|---|---|---|---|
| 2015-2019 | Corporate relocation wave, steady population growth | +6-8% | Toyota, Charles Schwab, and other HQ relocations to DFW |
| 2020-2022 | Pandemic migration, record-low rates, builder response | +15-18% | Homebuilders ramp construction aggressively across outer suburbs |
| 2023-2025 | Supply catches up, rate shock, apartment construction boom | -5% (2025 alone) | Nearly 97,000 new apartment units delivered in 2024 alone |
| 2026 (current) | Inventory absorption, sales volume recovering | ~0.2% (Zillow 12-month forecast) | Sales volume up 7.47% year over year despite flat pricing |
| 2027 (projected) | Rate easing, transaction volume growth | M&D Real Estate projects ~10% transaction volume growth | Continued population and job growth supporting gradual absorption |
Dallas’s correction differs meaningfully from Austin’s in character: Austin’s was driven by a demand collapse from tech sector layoffs and remote-work reversal layered onto pandemic overvaluation, while Dallas’s is driven almost entirely by builders overproducing supply into a still-intact demand base. That distinction matters for investors, since a supply-driven correction resolves through absorption over time rather than requiring a fundamental repricing of the metro’s long-term prospects.
Demographic Trends Driving Demand
- Corporate Headquarters Relocations – Toyota North America, Charles Schwab, Goldman Sachs, and dozens of other major employers have relocated or expanded significant operations to DFW over the past decade
- Fastest-Growing Outer Suburbs in the Nation – Princeton, Celina, Anna, and Melissa rank among the fastest-growing cities in the United States per recent Census data
- Telecom Corridor and Las Colinas – concentrated technology and corporate campus employment sustaining rental demand in Richardson, Plano, and Irving
- Financial Services Expansion – Goldman Sachs, Charles Schwab, and JPMorgan Chase have all expanded major DFW campuses, sustaining premium rental demand near Uptown and Legacy West
- DFW Airport Employment – American Airlines headquarters and the broader DFW Airport employment base anchor demand in Irving, Grapevine, and surrounding submarkets
- Genuinely Accessible Affordability – the income needed to buy at the median (~$109,242) against a metro median household income of ~$87,155 represents a smaller affordability gap than most major metros, sustaining broad-based demand
📚 New to real estate investing? Master the fundamentals with our professional course Learn more →
2. Neighborhood Hotspots
Dallas Investment Neighborhood Map
Interactive map of Dallas’s investment neighborhoods. Green stars show top hotspots, blue circles mark established markets, and orange circles highlight emerging areas.
Core Investment Neighborhoods
Detailed Submarket Analysis: All Dallas Neighborhoods
| Neighborhood | Price Range (SFH) | Cap Rate | Growth Drivers | Best Strategy |
|---|---|---|---|---|
| Bishop Arts / Oak Cliff | $270K-$450K | 5.5-7.0% | Walkability, affordability, gentrification momentum | Buy-and-hold, light value-add |
| Deep Ellum | $280K-$460K | 5.0-6.5% | DART access, cultural cachet, downtown proximity | Condo/loft rental, young professionals |
| Lake Highlands | $320K-$500K | 5.5-6.5% | Strong schools, low turnover, family stability | Family buy-and-hold |
| Oak Lawn | $300K-$500K | 5.0-6.0% | Walkability, medical district proximity, value versus Uptown | Condo rental, professional tenants |
| Garland | $260K-$400K | 6.0-7.5% | DART access, diversity, downtown revitalization | Cash flow focus, value entry |
| Uptown | $400K-$900K | 2.5-4.0% | Premium rents, highest Walk Score, nightlife | Pure appreciation, luxury rental |
| Preston Hollow | $700K-$2M+ | 2.5-3.5% | Affluent demographic, top schools | Long-term appreciation, luxury rental |
| Las Colinas / Irving | $280K-$500K | 5.0-6.0% | DFW Airport proximity, corporate campus employment | Corporate rental, balanced returns |
| Richardson / CityLine | $300K-$450K | 5.5-6.5% | Telecom Corridor employment, DART access | Balanced returns, professional tenants |
| Pleasant Grove | $180K-$280K | 7.5-9.5% | Deepest value entry point in Dallas proper | Best cash flow in the metro, value-add |
Expert Insight: “The mistake most out-of-state investors make in Dallas right now is chasing the lowest price tag in the fastest-growing outer suburb, places like Celina or Anna, without accounting for how much new supply is still coming online there. The better risk-adjusted opportunity is a neighborhood like Bishop Arts or Lake Highlands, where supply is naturally constrained by geography and existing development, and where the correction has been far milder because there simply wasn’t a construction boom to unwind.” – James Whitfield, Managing Partner, North Texas Property Partners
3. Property Types
| Investment Goal | Best Property Type | Best Neighborhoods | Minimum Capital |
|---|---|---|---|
| Maximum Cash Flow | Small multi-family or SFH in value corridors | Pleasant Grove, Garland, southern Dallas | $45,000+ |
| Best Balanced Returns | Value-add SFH or small multi-family | Bishop Arts, Oak Cliff, Deep Ellum | $70,000+ |
| Lowest Management | New construction suburban SFH | Richardson, Plano suburbs, Frisco | $80,000+ |
| Corporate Furnished Yield | Furnished condo or townhome | Uptown, Las Colinas, Legacy West | $90,000+ |
Don’t guess the costs. Our Complete Renovation & Remodeling Cost Guide covers 400+ pages of project-by-project breakdowns with real contractor pricing ranges.
4. Cost Analysis
Acquisition Cost Breakdown (Dallas)
| Expense Item | Typical Cost | Example ($350,000 Property) | Notes |
|---|---|---|---|
| Down Payment | 25% (investment) | $87,500 | Standard for investment properties in Texas |
| Closing Costs | 2-3% of price | $7,000-$10,500 | Title, escrow, lender fees, recording. No state transfer tax in Texas. |
| General Inspection | $400-$650 | $525 | Include foundation review given North Texas clay soil movement |
| MUD/PID Verification | Free (title search) | N/A | Critical in outer suburbs; Municipal Utility District and Public Improvement District levies can add 0.5-1.0% to effective tax rate |
| Initial Repairs | 0-7% of price | $0-$24,500 | Highly variable by neighborhood and property age |
| Reserves (6 months) | 6 months expenses | $10,000-$14,000 | Emergency fund for vacancy and repairs given elevated rental market vacancy in 2026 |
| TOTAL MINIMUM ENTRY | ~30-33% of value | $104,525-$116,525 | More affordable entry than Austin, roughly comparable to Houston |
Sample Cash Flow Analysis: Bishop Arts / Oak Cliff Single-Family Home
| Item | Monthly | Annual | Notes |
|---|---|---|---|
| Gross Rent | $2,150 | $25,800 | 3BR/2BA, Oak Cliff, renovated kitchen and bath |
| Less Vacancy (6%) | -$129 | -$1,548 | Conservative estimate given elevated 2026 metro-wide vacancy |
| Property Taxes | -$648 | -$7,770 | ~2.22% combined City of Dallas effective rate on $350,000 purchase price, no homestead exemption (investment property) |
| Insurance | -$155 | -$1,860 | Landlord policy reflecting Texas’s rising storm-related insurance costs |
| Property Management (9%) | -$194 | -$2,328 | Standard Dallas single-family management fee |
| Maintenance + CapEx | -$151 | -$1,812 | 7% of rent, moderate reserve for an older Oak Cliff home |
| Net Operating Income | $873 | $10,482 | Before mortgage |
| Mortgage ($350,000, 25% down, 6.5%, 30yr) | -$1,659 | -$19,908 | Principal and interest only |
| CASH FLOW | -$786 | -$9,426 | Negative on 25% down; positive with 35%+ down or an all-cash purchase |
| Cap Rate | 2.99% | NOI / Purchase Price (before renovation and rent growth upside) | |
| Total Return (4% appreciation) | ~12% | Including appreciation and principal paydown on leveraged purchase |
Dallas’s high property tax burden is the standout line item in this pro forma, running nearly as much as the mortgage’s monthly principal contribution and dramatically more than the property management fee. This is the structural reality Dallas investors must underwrite precisely: even in a genuinely functional cash flow market, the highest property tax burden among major Texas metros compresses net yields more than in Houston or San Antonio.
Expert Insight: “Dallas investors need to stop thinking of the metro as one market. A property in Pleasant Grove and a property in Celina can have the same purchase price but completely different risk profiles, one is buying into genuine, geography-constrained scarcity, and the other is buying into a construction boom that hasn’t finished absorbing yet. Model the specific ZIP code’s months of supply, not the metro average, before underwriting any deal.” – Patricia Nguyen, Senior Investment Analyst, DFW Capital Realty
5. Legal Framework
⚠️ Compliance Notice
Dallas follows the same statewide landlord-tenant law as the rest of Texas (Property Code Chapters 91-94), which remains broadly landlord friendly. This guide provides an overview only. Always consult a Texas-licensed real estate attorney before acquiring rental properties, and verify current Dallas Central Appraisal District figures directly for any specific property.
Dallas-Specific Regulations
Landlord-tenant law itself is governed statewide, and Dallas does not layer meaningful additional tenant protections on top of Texas Property Code, unlike Austin’s short-term rental overhaul:
- No Rent Control: The Texas Constitution (Article XI, Section 18) preempts local rent control entirely.
- No Statutory Deposit Cap: Landlords may charge any security deposit amount, subject to the 30-day return and itemization requirement under Tex. Prop. Code § 92.103.
- 3-Day Minimum Eviction Notice: The same statewide standard applies, per Tex. Prop. Code § 24.005.
- Habitability Duty: Landlords must make a diligent effort to repair conditions materially affecting health or safety after proper written notice, with a presumed 7-day reasonable repair window (§ 92.052).
- Property Tax Protest Rights: Dallas County property owners can file a formal appeal with the Dallas Central Appraisal District before the May 15 annual deadline, an important right given the county’s above-average effective rate.
- Municipal Utility District (MUD) and Public Improvement District (PID) Disclosure: Properties in outer suburbs are frequently subject to additional MUD or PID levies layered on top of standard property tax; sellers are generally required to disclose these, but investors should confirm directly with the title company.
- No Universal Rental Registration: Dallas does not require universal registration of long-term rental units, similar to Houston.
Compliance Best Practices
Systematic compliance protects Dallas investors from costly disputes even in a broadly landlord-friendly framework:
- Written Lease Requirement: Use a written lease specifying entry notice, late fees, and deposit terms explicitly, since Texas law leaves several areas to the lease itself rather than statute.
- Move-In Documentation: Photograph and date every room at move-in. Texas does not require a joint walk-through, so your own documentation is the primary protection in a deposit dispute.
- Itemized Deduction Discipline: Never withhold a deposit without a specific, itemized written breakdown; vague deductions have cost Texas landlords in small claims disputes.
- Annual Property Tax Protest: Given Dallas County’s above-average effective rate and DCAD’s mass appraisal model, protest the appraised value annually rather than treating it as fixed.
- Verify MUD/PID Status Before Purchase: Especially important in Princeton, Celina, Anna, Melissa, and other fast-growing outer suburbs where these levies can add meaningfully to the effective tax rate.
- Smoke Detector and Security Device Compliance: Statewide requirements under Texas Property Code Chapter 92 apply identically to Dallas.
- Professional Management: For any out-of-state investor with holdings spread across multiple DFW submarkets, professional management with cross-suburb experience is valuable given how differently individual ZIP codes are performing.
Useful Dallas Resources
- Dallas Central Appraisal District: dallascad.org
- Texas Attorney General Renter’s Rights: texasattorneygeneral.gov
- Texas Real Estate Research Center (TRERC): recenter.tamu.edu
- Texas State Law Library Landlord-Tenant Guide: guides.sll.texas.gov
| Regulation | Dallas Requirement | Compare: Austin | Investor Impact |
|---|---|---|---|
| Short-Term Rentals | No comparable citywide licensing overhaul as of 2026 | Sweeping 2025-2026 licensing overhaul with density caps | Dallas STR strategies face far less regulatory complexity than Austin |
| Property Tax Burden | Highest effective rate among major Texas metros (~2.22% City of Dallas) | Lower Travis County effective rate (~1.8%) | Dallas carries the heaviest recurring tax burden of the major Texas metros covered in this series |
| Eviction Notice | 3 days minimum (statewide) | Same statewide standard | Identical eviction process and timeline across both cities |
| Rent Control | Constitutionally preempted statewide | Same statewide preemption | No risk of local rent control in either city |
| MUD/PID Levies | Common in outer suburbs (Princeton, Celina, Anna, Melissa) | Common in suburban Austin developments too | Verify specific address before assuming the metro-average tax rate applies |
6. Step-by-Step Dallas Investment Playbook
Define Your Dallas Strategy
Dallas in 2026 supports genuinely different strategies depending on which ring of the metro you target. Before buying, be clear on which of these strategies you are executing:
Inner-City Cash Flow
Buy in supply-constrained inner-city neighborhoods that avoided the construction boom. Genuine cash flow supported by scarcity rather than builder concessions.
Corporate Furnished Rental
Buy near major corporate campuses (Uptown, Las Colinas, Legacy West) and target 30-90 day furnished stays for relocating executives and consultants from Dallas’s deep headquarters base.
Value-Add / BRRRR
Buy dated properties in Oak Cliff or Pleasant Grove. Renovate to increase rents and value. Refinance out equity, repeat. Dallas’s low acquisition basis in these corridors makes this capital-efficient.
Discounted New Construction
Negotiate hard on new construction in oversupplied outer suburbs, using builder concessions (rate buydowns, closing cost credits) to offset the near-term appreciation lag while positioning for absorption over 3-5 years.
Build Your Dallas Team
DFW’s sheer geographic sprawl (9,000+ square miles across four counties) means submarket-specific expertise matters as much here as in Houston. Non-negotiable team members:
- Dallas-Specialist Real Estate Agent: Must know specific submarket supply dynamics, since a great deal in Bishop Arts and an oversupplied deal in an unfamiliar outer suburb can look identical on paper.
- Property Tax Protest Specialist: Given Dallas County’s above-average effective rate, engaging a protest specialist (many work on contingency, no reduction, no fee) can meaningfully improve annual cash flow.
- Insurance Broker with Texas Storm Expertise: Get a written quote before waiving your inspection contingency, given the state’s rising homeowner insurance costs.
- Dallas-Licensed Property Manager: Verify specific experience in your target submarket given how unevenly the correction has hit different neighborhoods.
- Real Estate CPA familiar with the Texas market: For depreciation strategy, entity structuring, and Dallas County property tax appeal procedures.
Expert Tip: Ask any Dallas agent directly: “What is the current months-of-supply figure for this specific ZIP code, not the metro average?” A 4.1-month supply in a closer-in neighborhood and an 8+ month supply in an outer suburb represent fundamentally different negotiating positions, even at similar price points.
Dallas-Specific Due Diligence
Standard due diligence items plus these Dallas-critical checks:
Physical Due Diligence
- Foundation inspection specific to North Texas clay soil movement, a genuine risk factor in the metro
- Roof and gutter condition given hail exposure, a leading cause of Texas homeowner insurance claims
- HVAC condition and capacity given the region’s extreme summer heat load
- Termite and wood-destroying insect inspection given the humid climate
- Age and condition of plumbing, especially for pre-1980s cast iron or polybutylene pipe
Regulatory and Market Due Diligence
- Verify whether the property sits in a Municipal Utility District (MUD) or Public Improvement District (PID) with additional tax levies, especially in outer suburbs
- Pull current Dallas Central Appraisal District appraised value versus purchase price, and evaluate protest potential
- Check the specific ZIP code’s months-of-supply figure, not just the metro-wide average, since the correction is highly uneven
- Review HOA rules for rental restrictions if applicable, particularly in newer suburban developments
- Confirm insurance quote in writing before waiving the inspection contingency, given Texas’s rising storm-related premiums
Competing in Dallas’s Buyer-Favorable Market
With 5.4+ months of inventory and 21% of listings carrying price cuts, DFW in 2026 offers genuine negotiating leverage. Strategies that work:
- Negotiate hardest in the most oversupplied submarkets: Outer suburbs absorbing the bulk of 2023-2025 new construction offer the most builder and seller flexibility.
- Target listings with price cuts already applied: With 21% of DFW listings carrying reductions, these sellers have already signaled realistic pricing expectations.
- Use builder concessions as comps leverage: New-home rate buydowns and closing cost credits in fast-growing suburbs can be used as negotiating leverage on comparable resale listings nearby.
- Move quickly in tighter closer-in submarkets: Homes in Dallas still sell in around 40 days on average with 2 offers per listing, meaning genuinely well-priced inner-city inventory can still move with some competition.
- Request seller-paid rate buydowns metro-wide: With rates in the 6-7% range, a funded buydown can materially improve first-year cash flow without requiring a price reduction.
Property Management in Dallas
DFW’s rental market oversupply and geographic sprawl make submarket-specific rent pricing and active management particularly important in 2026. Key management focuses:
Rent Pricing in an Oversupplied Market
With rents essentially flat year over year metro-wide, pricing discipline matters more than during the 2021-2022 boom:
- Pull current comparable listings within the immediate submarket before setting or renewing rent, not stale year-old comps
- Expect to offer modest concessions on new listings in apartment-heavy submarkets given elevated vacancy from the 2024 construction wave
- Single-family rentals in supply-constrained inner-city neighborhoods are generally more resilient than apartment-style product in oversupplied outer suburbs
- Budget realistic days-to-lease of 20-35 days in the current environment
Typical Dallas Management Fees
- Single-family management: 8-10% of monthly rent
- Multi-family management: 6-9% of monthly rent
- Leasing fee: 50-100% of one month’s rent
- Lease renewal fee: $150-$300 per renewal
- Furnished/corporate rental management: Often 15-25% given higher turnover intensity
7. Financing Options for Dallas
| Loan Type | Down Payment | Rate Premium | Best For | Dallas Note |
|---|---|---|---|---|
| Conventional Investment | 20-25% | +0.5-0.75% | Strong W-2 income, good credit | Most Dallas properties stay comfortably under conforming loan limits |
| DSCR Loan | 20-25% | +1-2% | Investors who want no income verification | Dallas’s roughly 5.4% gross yield generally supports DSCR qualification better than Austin, though the high property tax burden can offset the yield advantage in some ZIP codes |
| Portfolio Loan | 20-25% | +1-1.75% | Multiple properties, self-employed | Deep regional bank presence (Frost Bank, Independent Bank, Comerica) active in DFW |
| House Hacking (FHA) | 3.5% | Standard + MIP | Owner-occupying one unit of 2-4 unit property | Excellent entry point given Dallas’s genuinely accessible affordability gap relative to income |
| Builder Rate Buydowns | Standard | 1-2 points below market for 1-3 years | New construction purchases in fast-growing suburbs | Increasingly common concession given elevated new-home inventory |
| Hard Money (Bridge) | 15-25% | 9-13% rate | BRRRR acquisitions, fast closings | Active hard money lender base given DFW’s established flip and BRRRR investor community |
Dallas Financing Reality: Dallas’s roughly 5.4% metro-wide gross yield generally supports DSCR loan qualification better than Austin, though investors should model the property tax burden carefully, since Dallas County’s 2.2%+ effective rate can meaningfully reduce net operating income relative to the gross yield figure. Properties in lower-tax suburbs like Mesquite or Balch Springs can show materially better DSCR math than a comparable property inside Dallas ISD boundaries.
8. Frequently Asked Questions

Knowledge Quiz: Dallas Real Estate Investment
Open Quiz
5 quick questions on what you just learned about Dallas investing
1) What is the primary driver of Dallas’s 2026 price correction, according to the guide?
Answer: B
Dallas’s correction is fundamentally a supply-side story. Homebuilders built aggressively for pandemic-era demand, and now supply is catching up, with unemployment at just 3.6% and sales volume actually up year over year, confirming demand has not collapsed.
2) Approximately what gross rental yield does the guide cite for the Dallas metro, making it one of the more functional cash flow markets among major U.S. metros?
Answer: C
A Zillow home value of roughly $362,720 against a rent index of $1,632/month produces a gross annual yield of approximately 5.4%, a genuinely workable cash flow setup rare among major Sun Belt metros in 2026.
3) Why does the guide caution against assuming the lowest-priced Dallas outer suburbs are automatically the best deal?
Answer: D
Fast-growing suburbs like Princeton, Celina, Anna, and Melissa absorbed most of the new construction wave, meaning oversupply risk is highest there even though long-term population growth fundamentals remain genuinely strong.
4) What does the guide identify as the standout expense line item that distinguishes Dallas from Houston or San Antonio in cash flow underwriting?
Answer: A
Dallas County’s combined effective property tax rate (~2.22% for a typical City of Dallas property) is the highest among major Texas metros and the third highest among populous U.S. counties, making it the standout recurring expense line item.
5) How does Dallas’s short-term rental regulatory environment compare to Austin’s, per the guide?
Answer: B
Unlike Austin, which underwent a sweeping short-term rental licensing overhaul with distance rules and density caps in 2025-2026, Dallas has no comparable citywide STR regulatory framework, meaning Dallas STR strategies face far less regulatory complexity.
Work With a Local Expert in Dallas
We are building a verified network of real estate professionals across every market we cover.

About Our Expert Network
We are finalizing partnerships with verified real estate professionals across every market featured on Builds and Buys. Each expert in our network is selected for their hands-on investment experience, local market knowledge, and commitment to helping buyers and investors make sound decisions.
Our local specialists offer:
- Proven experience with investment and income-producing properties
- Deep knowledge of local pricing, rental yields, and neighborhood dynamics
- Guidance on financing, legal structure, and due diligence
- Access to off-market and pre-market opportunities
- Full transaction support from search through closing
- Ongoing portfolio and property management referrals
Services Covered
- Property sourcing and acquisition
- Investment analysis and underwriting
- Buyer representation
- Market comparables and valuations
- Short-term and long-term rental strategy
- Value-add and renovation guidance
- Legal and title referrals
- Financing and lender connections
- Property management referrals
- Insurance and inspection referrals
- 1031 exchange coordination
- Exit strategy planning
Get Connected or Join Our Network
Looking for a local expert to help with your investment? Reach out and we will connect you with the right professional for your market and strategy.
Are you a real estate professional with a track record working with investors? We are always expanding our network of verified local experts.
Contact us at support@buildsandbuys.com
Find Specialized Dallas Real Estate Professionals
Ready to Invest in Dallas?
Dallas-Fort Worth in 2026 offers one of the more genuinely balanced investment cases among major U.S. metros. A builder-driven supply correction, not a demand collapse, has handed buyers real negotiating leverage while employment, population growth, and a deep corporate headquarters base remain fully intact. The metro’s roughly 5.4% gross rental yield is genuinely workable, a rarity among major Sun Belt markets in 2026, though investors must underwrite Dallas County’s above-average property tax burden carefully and choose submarkets with an eye toward which neighborhoods absorbed the construction boom and which stayed naturally supply-constrained.
Continue Your Research
Texas State Guide
See how Dallas compares to Houston, Austin, San Antonio, and other Texas markets.
Step-by-Step Invest
Complete framework for building a real estate investment strategy from scratch.
144-Lesson Course
University-level real estate education covering financing, law, strategy, and management.
For further guidance, explore our State-by-State Investor guides, browse our expert articles, or follow our Step-by-Step Investment Guide.