Fort McMurray Real Estate Investment Guide For 2026
A comprehensive resource for investors looking at Fort McMurray, the centre of the Athabasca oil sands and the most cyclical housing market in Alberta, where high incomes and the province’s strongest yields come with real boom, bust, wildfire, and flood risk in 2026. All figures in Canadian dollars.
Quick answers: Top 5 most searched Fort McMurray investment questions ▼
Migration data: Where people are moving from to Fort McMurray ▼
In This Guide
Click on any section to navigate directly to that content
1. Fort McMurray Market Overview
Market Fundamentals
Fort McMurray is the urban centre of the Regional Municipality of Wood Buffalo in northeastern Alberta, and the hub for the Athabasca oil sands, one of the largest oil deposits in the world. It has some of the highest household incomes in Canada and some of the most volatile housing history, shaped by the 2014 oil collapse, the 2016 wildfire, the 2020 flood, and 2024 wildfire evacuations.
Key economic indicators that define Fort McMurray’s investment case:
- Population: About 70,000+ in the urban area, plus a large camp based workforce
- Major Employers: Oil sands producers, contractors, services, and the municipality
- Avg Detached Price: About $532,600 (May 2026), up about 15% year over year
- Months of Supply: About 2.6 (May 2026)
- Governance: Regional Municipality of Wood Buffalo
- No Provincial Sales Tax or Land Transfer Tax: Only Land Titles registration fees
Fort McMurray’s economy depends almost entirely on the oil sands. Production has grown even as companies shifted toward camp based and rotational work, which reduced the share of workers living in town.
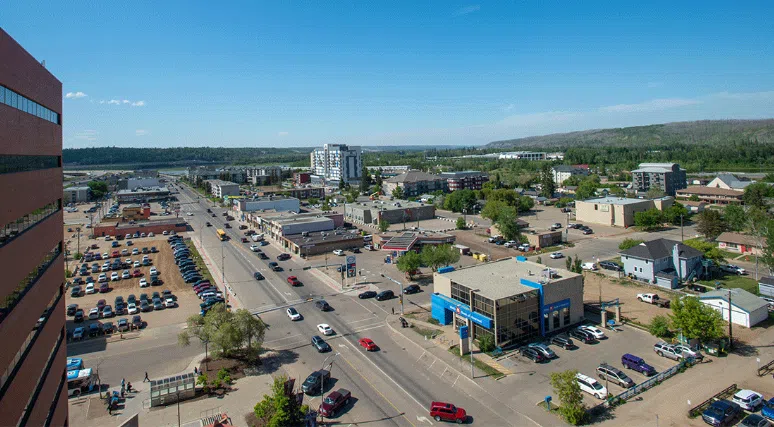
Fort McMurray sits at the confluence of the Athabasca and Clearwater rivers
2026 Economic Outlook
- Oil sands production and oil prices
- Rising prices and tight supply in 2026
- Wildfire and flood risk management
- Camp based workforce trends
- Rebuilt neighbourhoods after 2016
Investment Climate
Fort McMurray’s 2026 environment is a recovery with real risk. Successful investors here tend to share a few characteristics:
- Large reserves
- Full insurance for fire and flood
- Cash flow focus
- Downturn planning
- Experience with volatile markets
Alberta’s landlord friendly law and lack of land transfer tax apply. Fort McMurray’s main risks are economic concentration and natural hazards.
Historical Performance
| Period | Market Driver | Price Trend | Key Event |
|---|---|---|---|
| 2010-2014 | Oil sands boom | Peak prices | Very high rents |
| 2015-2019 | Oil collapse, 2016 wildfire | Sharp declines | Entire city evacuated in 2016 |
| 2020-2022 | Flood, pandemic, recovery | Bottoming | 2020 ice jam flood |
| 2023-2024 | Production growth | Recovery | 2024 wildfire evacuations |
| 2025-2026 | Tight supply | Rising (about +15% YoY, May 2026) | Recovery continues |
Fort McMurray investors who bought near the 2014 peak suffered large losses. Those who bought after the downturn have seen strong recoveries. Timing and reserves matter more here than anywhere else in Alberta.
Demographic Trends Driving Demand
- Oil Sands Workers – High incomes
- Contractors – Turnaround and project workers
- Families – Year round residents
- Services – Retail, healthcare, and education
- Rotational Workers – Furnished rental demand
- Camp Housing – Reduces in town rental demand
📚 New to real estate investing? Master the fundamentals with our professional course Learn more →
2. Neighbourhood Hotspots
Fort McMurray Investment Neighbourhood Map
Interactive map of Fort McMurray’s investment neighbourhoods. Green stars show top hotspots, blue circles mark established markets, and orange circles highlight emerging areas. All figures in Canadian dollars.
Core Investment Neighbourhoods
Detailed Submarket Analysis: Fort McMurray Neighbourhoods
| Neighbourhood | Price Range | Cap Rate | Growth Drivers | Best Strategy |
|---|---|---|---|---|
| Downtown / Waterways | $120K-$450K | 6.5-9.5% | Lowest entry | Experienced investors, flood and fire risk |
| Gregoire | $150K-$350K | 7.0-9.0% | Industrial proximity | Value add, higher risk |
| Dickinsfield | $280K-$450K | 6.5-8.0% | Affordability | Suites, townhomes |
| Thickwood / Wood Buffalo | $340K-$580K | 5.2-6.5% | Suite friendly stock | Suite conversions |
| Timberlea / Stone Creek | $380K-$650K | 5.0-6.5% | Deep tenant pool | Legal suited homes |
| Eagle Ridge / Parsons Creek | $450K-$700K | 4.6-5.8% | Newest stock | Family rentals |
| Abasand / Beacon Hill | $400K-$600K | 4.8-6.0% | Rebuilt homes | Newer stock, wildfire exposure |
Investor Insight: Fort McMurray investors need to plan for three kinds of shocks: oil price downturns that cut jobs, wildfires like 2016 and 2024 that can force evacuations, and river flooding like 2020. Each can interrupt rent and damage property. Insurance, reserves of at least six to twelve months, and a property that still works if rents fall are not optional here.
3. Property Types
| Investment Goal | Best Property Type | Best Neighbourhoods | Minimum Capital |
|---|---|---|---|
| Maximum Cash Flow | Legal suited home or duplex | Timberlea, Thickwood, Dickinsfield | $120,000+ |
| Long Term Appreciation | Detached home in a family area | Eagle Ridge, Stone Creek, Timberlea | $130,000+ |
| Balanced Returns | Older home plus a new legal suite | Thickwood, Dickinsfield, Downtown | $170,000+ |
| Lowest Management | Newer home with a legal suite | Parsons Creek, Stone Creek, Eagle Ridge | $120,000+ |
Don’t guess the costs. Our Complete Renovation & Remodeling Cost Guide covers 400+ pages of project-by-project breakdowns with real contractor pricing ranges.
4. Cost Analysis
Acquisition Cost Breakdown (Fort McMurray)
| Expense Item | Typical Cost | Example ($500,000 Suited Home) | Notes |
|---|---|---|---|
| Down Payment | 20% minimum (rental) | $100,000 | Default insurance is not available on non owner occupied property |
| Land Transfer Tax | None in Alberta | $0 | A major advantage over Ontario and British Columbia |
| Land Titles Transfer Fee | $50 + $5 per $5,000 of value | $550 | Rate in effect since October 20, 2024 |
| Mortgage Registration Fee | $50 + $5 per $5,000 of mortgage | $450 | On a $400,000 mortgage |
| Legal Fees and Disbursements | $1,200-$1,900 | $1,600 | Real estate lawyer handles title, funds, and registration |
| Home Inspection | $450-$750 | $550 | Inspect both units and the suite separation |
| Sewer Line Camera Scope | $250-$400 | $300 | Recommended on older homes with mature trees |
| Appraisal and Title Insurance | $600-$1,000 | $800 | Lender appraisal plus title insurance where used |
| Setup and Initial Repairs | 0-5% of price | $2,000 | Locks, cleaning, smoke and CO alarms in both units |
| Reserves | 3-6 months of expenses | $15,000 | Vacancy, furnace, hot water tank, and winter repairs |
| TOTAL MINIMUM ENTRY | ~24% of value | $121,250 | No land transfer tax keeps Alberta entry costs low |
Sample Cash Flow Analysis: Timberlea Home Home with Legal Suite
| Item | Monthly | Annual | Notes |
|---|---|---|---|
| Upper Unit Rent | $2,150 | $25,800 | 3BR upper level |
| Basement Suite Rent | $1,500 | $18,000 | 2BR legal basement suite |
| Gross Income | $3,650 | $43,800 | Utilities split between tenants |
| Less Vacancy (7%) | -$256 | -$3,066 | Higher allowance for a volatile market |
| Property Taxes | -$312 | -$3,750 | Approximate, verify on the Regional Municipality of Wood Buffalo tax notice |
| Insurance | -$267 | -$3,200 | Landlord policy covering two units |
| Property Management (8%) | -$292 | -$3,504 | Optional for local investors who self manage |
| Maintenance + CapEx (10%) | -$365 | -$4,380 | Two kitchens, two bathrooms |
| Net Operating Income | $2,158 | $25,900 | Before mortgage |
| Mortgage ($400,000, 20% down, 4.99%, 25yr) | -$2,324 | -$27,890 | Principal and interest, Canadian semi annual compounding |
| CASH FLOW | -$166 | -$1,990 | About +$126/month if self managed |
| Same deal at 30% down | $125 | $1,496 | About +$417/month if self managed |
| Cap Rate | 5.18% | NOI / Purchase Price (gross yield 8.8%) | |
| Total Return Year 1 (3% appreciation assumed) | ~18% | Cash flow + $8,321 principal paydown + $15,000 appreciation on $121,250 invested |
This is the honest Fort McMurray picture in 2026. A well bought legal suited home runs -$166 a month with full property management at 20% down, about $126 a month if you self manage, and about $417 a month self managed at 30% down. Without the suite, the same house would rent for about $2,450 in total and run roughly -$1,066 a month after the mortgage, which is why the suite drives the strategy. The appreciation figure is an assumption, not a forecast. Rates and rents are examples only, so run your own numbers on every deal.
Investor Insight: Rotational and camp based work means some oil sands employees never rent in town. Focus on families and workers who live in Fort McMurray year round, and treat furnished short stay demand as a bonus rather than the base case.
5. Legal Framework
⚠️ Alberta Compliance Notice
Residential tenancies in Fort McMurray are governed by Alberta’s Residential Tenancies Act, the Minimum Housing and Health Standards, the Alberta Human Rights Act, and the Regional Municipality of Wood Buffalo land use and building rules. Alberta is landlord friendly, but the rules on notices, deposits, and inspections are strictly applied, and a defective notice can restart your timeline. This guide is an overview as of October 2026. Confirm current rules with Service Alberta, the Regional Municipality of Wood Buffalo, and an Alberta real estate lawyer before you buy.
Alberta and Fort McMurray Regulations
The rules that matter most to Fort McMurray landlords:
- No Rent Control: There is no cap on the amount of a rent increase. Rent can rise only once every 365 days.
- Rent Increase Notice: At least three full tenancy months of written notice on a monthly periodic tenancy. Rent cannot be raised during a fixed term lease.
- Fixed Term Leases: A fixed term tenancy ends on its stated end date. The landlord is not required to renew, which gives Alberta landlords far more flexibility than in Ontario or British Columbia.
- Security Deposits: Capped at one month’s rent and placed in a trust account within two banking days. Interest is set yearly by the province, and the 2026 rate is 0%.
- Inspection Reports: Move in and move out inspection reports are mandatory. A landlord who skips them cannot deduct from the deposit.
- Deposit Return: Within 10 days after the tenant gives up possession, with an itemized statement for any deductions.
- Ending a Periodic Tenancy: A landlord can end a monthly periodic tenancy only for reasons set out in the Act, such as sale with vacant possession, landlord or family occupancy, demolition, or major renovation, with three full tenancy months of notice.
- Substantial Breach: A 14 day notice can be served for non payment or other substantial breach.
- Fort McMurray Land Use: The Regional Municipality of Wood Buffalo allows secondary suites in a number of residential districts with development and building permits. Confirm the district for each lot with the municipality.
Compliance Best Practices
Running Fort McMurray rentals smoothly comes down to documentation:
- Written Leases: Use an Alberta specific lease that reflects the Residential Tenancies Act. Any clause that conflicts with the Act is void.
- Inspection Reports: Complete and sign move in and move out reports with dated photos for every unit.
- Trust Account: Hold every security deposit in a dedicated trust account and track the provincial interest rate each year.
- Entry Notice: Give at least 24 hours written notice before entering, for a valid reason, at a reasonable time.
- Suite Legality: Keep development permits, building permits, and final inspections for every suite on file.
- Fair Screening: Apply consistent written criteria to every applicant in line with the Alberta Human Rights Act.
Useful Fort McMurray Resources
- Alberta Residential Tenancies: alberta.ca/renting-and-leasing
- Residential Tenancy Dispute Resolution Service: alberta.ca/rtdrs
- Regional Municipality of Wood Buffalo: rmwb.ca
- Alberta Emergency Alert (wildfire and flood): alberta.ca/alberta-emergency-alert
| Regulation | Alberta (Fort McMurray) | Ontario / British Columbia | Investor Impact |
|---|---|---|---|
| Rent Control | None | Annual guideline caps on most tenancies | Rents can be reset to market each year |
| Fixed Term Ending | Ends on the end date | Generally continues or converts to monthly | More control over who stays |
| Rent Increase Notice | 3 tenancy months, once per 365 days | Similar notice, but capped amount | Plan increases on a 12 month calendar |
| Security Deposit | Up to one month, held in trust | Ontario bans damage deposits. BC caps at half a month | Better protection against damage |
| Disputes | RTDRS or court | Provincial tribunals, often with long backlogs | Faster resolution in most cases |
| Land Transfer Tax | None. Registration fees only | Tiered tax, plus municipal tax in Toronto | Thousands saved on every purchase |
6. Step-by-Step Fort McMurray Investment Playbook
Define Your Fort McMurray Strategy
Be clear on which strategy you are executing before you shop in Fort McMurray:
Suited Home Buy-and-Hold
Buy a home that already has a permitted suite. Two rents, one title, and lender recognized income.
Add-a-Suite Value Add
Buy an unsuited home below market and add a legal suite to lift income and value.
Family Rental Hold
Rent a detached home to a long term family tenant and accept thinner cash flow for stability.
Townhome or Duplex Entry
Start with a well run townhome or a duplex to keep capital requirements low.
Build Your Fort McMurray Team
The right team keeps you out of the most common Alberta mistake, which is paying suite prices for a suite that is not legal:
- Investor Focused Realtor: Someone who can pull permit history, understands suite income, and knows local zoning.
- Mortgage Broker: Access to lenders with different rental income treatment, offset versus add back, which can change how much you qualify for.
- Alberta Real Estate Lawyer: Handles title, Real Property Report or title insurance, Land Titles registration, and condo document review.
- Suite Experienced Contractor: Knows fire separation, egress windows, smoke and CO interconnection, and municipal permit requirements.
- Property Manager: Licensed under the Real Estate Act and fluent in Residential Tenancies Act notices and RTDRS procedure.
- Accountant: For Capital Cost Allowance, suite construction cost treatment, and ownership structure.
Expert Tip: Ask any property manager you interview: “Walk me through how you serve a 14 day substantial breach notice and when you file with the RTDRS.” Then ask: “How do you handle the trust account and annual interest on security deposits?” Clear, specific answers mean they know Alberta law. Vague answers mean they do not.
Fort McMurray-Specific Due Diligence
Standard due diligence plus these local checks:
Physical Due Diligence
- Wildfire exposure and FireSmart measures on the lot
- Flood mapping in the river valley and lower town
- Furnace and hot water tank age, given long cold winters
- Frozen pipe history and insulation
- Foundation cracks and lot grading
- Suite fire separation and egress windows
- Rebuild quality and permits on post 2016 homes
Regulatory Due Diligence
- Confirm development and building permits for any existing suite
- Check the land use district and the units allowed on the lot
- Review the Real Property Report with compliance, or arrange title insurance
- Review existing leases, deposits held, and inspection reports if tenanted
- For condos, review the reserve fund study, budget, minutes, and bylaws
- Confirm short term rental licensing and condo bylaws if planning STR
- Check GST status on new or substantially renovated homes
Buying in Fort McMurray’s 2026 Market
Fort McMurray is rising in 2026. Strategies that work:
- Insurance first: Get wildfire and flood coverage quotes before you go firm.
- Stress test the deal: Assume lower rents and higher vacancy in a downturn.
- Verify the suite: Ask for permits and final inspections. Price unpermitted suites as single family homes.
- Check flood mapping: Especially downtown and in lower town.
- Hold large reserves: Six to twelve months of expenses per property.
Property Management in Fort McMurray
Fort McMurray management requires plans for evacuations, insurance claims, and rapid shifts in demand:
Tenant Screening Protocol
Alberta lets landlords choose among qualified applicants, provided the process does not discriminate under the Alberta Human Rights Act. A strong process:
- Publish clear written criteria covering income, references, and credit
- Verify income with pay stubs or an employment letter
- Call at least two previous landlords
- Run a credit check with written consent
- Apply the same criteria to every applicant and keep records
Typical Fort McMurray Management Fees
- Single family management: 8-10% of monthly rent
- Suited homes: often 8-10% per unit
- Leasing fee: 50-100% of one month’s rent
- Lease renewal fee: $0-$250
- Winter readiness and furnace servicing billed separately
7. Financing Options for Fort McMurray
| Loan Type | Down Payment | Rate Context | Best For | Fort McMurray Note |
|---|---|---|---|---|
| Conventional Rental Mortgage | 20% minimum | Usually above insured rates | Most rental purchases | Must pass the federal stress test |
| Owner Occupied Suited Home | From 5% (insured) | Lowest available rates | House hacking: live upstairs, rent the suite | Best entry point for new investors |
| Owner Occupied 3-4 Units | From 10% (insured) | Insured rates | Owner living in one unit | Strong option where zoning allows multiple units |
| Credit Union / Portfolio | 20-35% | Varies by lender | Multiple properties, self employed | Alberta credit unions are active rental lenders |
| CMHC MLI Select (5+ units) | As low as 5% on qualifying projects | Insured multi unit rates | Larger rental builds and purchases | Requires affordability, energy, or accessibility commitments |
| Purchase Plus Improvements | 20% of total cost (rental) | Conventional rates | Buying and adding a legal suite | Funds held back until work is completed |
| Private / Alternative Lender | 20-35% | Higher rates plus fees | Short term renovation or bridge | Exit plan to conventional financing required |
Fort McMurray Financing Reality: As of September 2026 the Bank of Canada held its policy rate at 2.25%, and the average conventional five year fixed rate in Canada was about 5.1%, with the best insured rates near 4.1 to 4.4%. Rental mortgages require 20% down because default insurance is not available on property you do not occupy, and you must qualify at the higher of 5.25% or your contract rate plus 2%. How a lender counts rental income, either offsetting it against the mortgage or adding a portion to your income, can make a large difference to how much you qualify for. A broker who shops several lenders is worth it in this market. Some lenders apply stricter terms in single industry towns. Confirm lender policies for Fort McMurray early in the process.
8. Frequently Asked Questions

Knowledge Quiz: Fort McMurray Real Estate Investment
Open Quiz
5 quick questions on what you just learned about Fort McMurray investing
1) What is the minimum down payment on a Fort McMurray rental you will not live in?
Answer: C
Default insurance is not available on rental property you do not occupy, so lenders require at least 20% down, and you must still pass the federal stress test.
2) Which risks are unique in Fort McMurray compared with most Alberta markets?
Answer: B
Fort McMurray has faced the 2014 oil price collapse, the 2016 wildfire, the 2020 flood, and 2024 wildfire evacuations.
3) How much reserve should Fort McMurray investors hold?
Answer: C
Because of cycle, fire, and flood risk, Fort McMurray investors should hold much larger reserves than in most markets.
4) How often can rent be increased in Alberta, and how much notice is needed on a monthly periodic tenancy?
Answer: C
Alberta has no rent control. Rent can rise by any amount once every 365 days, with three full tenancy months of written notice on a monthly periodic tenancy, and cannot rise during a fixed term lease.
5) What happens at the end of a fixed term lease in Alberta?
Answer: B
Unlike Ontario and British Columbia, a fixed term tenancy in Alberta ends on its end date. Landlords and tenants can sign a new lease, often at a new rent, but there is no automatic renewal.
Work With a Local Expert in Fort McMurray
We are building a verified network of real estate professionals across every market we cover.

About Our Expert Network
We are finalizing partnerships with verified real estate professionals across every market featured on Builds and Buys. Each expert in our network is selected for their hands-on investment experience, local market knowledge, and commitment to helping buyers and investors make sound decisions.
Our local specialists offer:
- Proven experience with investment and income-producing properties
- Deep knowledge of local pricing, rental yields, and neighbourhood dynamics
- Guidance on financing, legal structure, and due diligence
- Access to off-market and pre-market opportunities
- Full transaction support from search through closing
- Ongoing portfolio and property management referrals
Services Covered
- Property sourcing and acquisition
- Investment analysis and underwriting
- Buyer representation
- Market comparables and valuations
- Short-term and long-term rental strategy
- Value-add and renovation guidance
- Legal and title referrals
- Financing and lender connections
- Property management referrals
- Insurance and inspection referrals
- Secondary suite and permit guidance
- Exit strategy planning
Get Connected or Join Our Network
Looking for a local expert to help with your investment? Reach out and we will connect you with the right professional for your market and strategy.
Are you a real estate professional with a track record working with investors? We are always expanding our network of verified local experts.
Contact us at support@buildsandbuys.com
Find Specialized Fort McMurray Real Estate Professionals
Ready to Invest in Fort McMurray?
Fort McMurray is Alberta’s highest yielding and highest risk major rental market. High incomes and a recovering 2026 market create real opportunity, while oil cycles, wildfire, and flooding create real danger. Experienced investors with large reserves, full insurance, and a long horizon can profit here. Beginners should start somewhere less volatile.
Continue Your Research
Alberta Province Guide
See how Fort McMurray compares to Grande Prairie, Cold Lake, and other Alberta markets.
Step-by-Step Invest
Complete framework for building a real estate investment strategy from scratch.
144-Lesson Course
University-level real estate education covering financing, law, strategy, and management.
For further guidance, explore our Canadian Province guides, browse our expert articles, or follow our Step-by-Step Investment Guide.