Park City Real Estate Investment Guide For 2026
A comprehensive resource for investors targeting Utah’s premier destination resort community, where Park City Mountain Resort and Deer Valley draw millions of annual visitors, the Sundance Film Festival anchors a global cultural identity, and a mature short-term rental market creates an investment profile fundamentally different from every metro market in this Utah series
Quick answers: Top 5 most searched Park City investment questions ▼
Visitor data: Who visits and buys in Park City and why ▼
1. Park City Market Overview
Market Fundamentals
Every other guide in this Utah series has addressed some version of the same investor: someone seeking residential rental income, whether from long-term tenants, students, or military families, with appreciation as a secondary benefit. Park City requires the investor to think completely differently. The primary tenant is an overnight guest, not a resident. The revenue cycle is seasonal and event-driven rather than monthly and lease-driven. The regulatory environment governs nightly rentals, not month-to-month tenancy. And the entry capital required is several multiples of anywhere else in this series.
Key facts about the Park City market:
- Year-Round Population: Approximately 8,500 within Park City limits; Summit County overall around 45,000
- Major Resorts: Park City Mountain Resort (largest ski resort in the U.S. by skiable acreage, owned by Vail Resorts) and Deer Valley Resort (ski-only luxury resort)
- Sundance Film Festival: Annual late-January event with global media presence and premium short-term lodging demand
- Airport Access: Salt Lake City International Airport approximately 35-45 minutes via I-80, providing direct national and international flight access
- Median Home Price: $2.1M+ city-wide; resort zoning condos starting around $700,000
- Property Owner Profile: The majority of Park City property owners are second-home owners or investors, not full-time residents
The Park City investment thesis is built on three pillars that do not exist together anywhere else in Utah: a year-round destination visitor base (winter skiing, summer mountain biking and golf, and event tourism), a globally recognized brand identity (Sundance, Olympic legacy from the 2002 Winter Games, Vail Resorts ownership of Park City Mountain), and one of the most geographically and politically constrained land supplies in the western U.S. (mountain terrain, conservation easements, and Summit County growth restrictions limit new development).
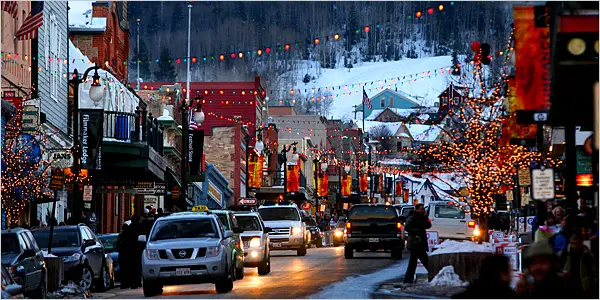
Park City’s Main Street, Park City Mountain Resort, and Deer Valley together form one of the most recognized destination resort identities in North America
2026 Market Factors
- Vail Resorts ongoing investment in Park City Mountain Resort infrastructure and lift capacity
- Deer Valley East Village expansion adding new ski terrain and associated real estate development
- Continued national recognition of Park City’s summer mountain biking and golf as a shoulder-season driver
- Summit County growth and conservation policy continuing to constrain new supply
- Ongoing national high-net-worth migration to mountain resort second-home markets
Investment Climate
Park City’s investment climate differs from every other market in this series along several dimensions that fundamentally change how an investor should think about the opportunity:
- Revenue is event and season-driven, not monthly. A Park City STR property’s annual revenue might be earned 40 percent in the ski season (December-March), 10-15 percent in a single Sundance week, 25-30 percent in summer (June-September), and the remainder in shoulder seasons. Understanding this revenue distribution is essential to evaluating any specific property’s earning potential.
- The market is capital-intensive, not leverage-friendly. Entry prices of $700,000 to $3M+ combined with jumbo financing requirements and often 30-40 percent down payments for second homes or investment properties mean Park City requires substantially more capital per unit of exposure than any other market in this series.
- Regulatory zoning is the primary risk factor, not market demand. Demand for Park City lodging is not in question; the question for any specific property is whether it is legally permitted to operate as an STR, and under what conditions. This is the single most important due diligence question in this market.
- Appreciation has historically outpaced cash-on-cash return as the primary wealth driver. Park City real estate has appreciated substantially over multi-decade periods, driven by land scarcity and growing national recognition of mountain resort real estate as an asset class. STR income offsets ownership costs; appreciation is often the larger component of total return for long-term holders.
Historical Performance
| Period | Market Driver | Avg Annual Appreciation | Key Event |
|---|---|---|---|
| 2010-2015 | Post-recession recovery, slow resort market recovery | 3-6% | Resort real estate recovered more slowly than primary residential markets nationally following the 2008 downturn |
| 2016-2019 | Vail Resorts acquisition of Park City Mountain, growing national recognition | 8-12% | Vail Resorts combined Park City Mountain and Canyons Resort into the largest connected ski resort in the U.S., elevating the destination profile substantially |
| 2020-2022 | Pandemic second-home demand surge | 20-28% | Mountain resort markets nationally experienced enormous demand surges as high-net-worth buyers sought second homes with outdoor access; Park City was among the strongest-performing U.S. resort markets |
| 2023-2024 | Rate adjustment, resort market normalization | 3-7% | Resort markets nationally normalized from pandemic peaks; Park City held value better than many comparable resort markets given Vail Resorts ownership stability and ongoing development |
| 2025-2026 | Rate stabilization, Deer Valley expansion, continued resort demand | 8-12% (projected) | Deer Valley East Village expansion adding terrain and real estate product; continued national high-net-worth interest in mountain resort assets |
Demand Drivers
- Park City Mountain Resort – Owned and operated by Vail Resorts, this is the largest connected ski resort in the United States by skiable acreage following the 2015 combination of the former Park City and Canyons resorts. Epic Pass access drives enormous visitor volume from across the country.
- Deer Valley Resort – A ski-only (no snowboarding) luxury resort known for exceptional grooming, limited daily ticket sales, and high-end service standards. Deer Valley’s real estate commands the highest prices in the Park City market and attracts an ultra-high-net-worth buyer and renter profile.
- Sundance Film Festival – The most prestigious independent film festival in North America, held annually in late January, bringing global media attention and a surge of premium short-term lodging demand to Park City for approximately 10 days.
- Summer Outdoor Recreation – Park City’s mountain biking trail network is internationally recognized, and the area’s golf courses and cooler mountain summer climate create a genuine summer destination season that gives Park City higher year-round occupancy than many single-season resort towns.
- Land Scarcity and Conservation Policy – Summit County’s growth management policies, conservation easements, and the mountainous terrain itself constrain new development. This permanent supply limitation underlies the long-term appreciation thesis.
- National High-Net-Worth Second-Home Demand – Park City benefits from a broader national trend of wealth concentration driving demand for mountain resort second homes, a trend that has supported resort real estate markets across Colorado, Utah, Wyoming, and Montana.
📚 New to real estate investing? Master the fundamentals with our professional course Learn more →
2. Neighborhood Hotspots
Park City Investment Neighborhood Map
Interactive map of Park City investment neighborhoods. Green stars show top investment hotspots, blue circles mark established markets, and orange circles highlight emerging or value corridors.
Core Investment Areas
Detailed Submarket Analysis
| Area | Price Range | Gross STR Yield | Demand Profile | Best Strategy |
|---|---|---|---|---|
| Old Town / Main Street | $1.2M-$3.5M | 4.0-5.5% | Maximum visitor demand, Sundance epicenter | Premium STR, Sundance positioning |
| Deer Valley / Empire Pass | $2M-$10M+ | 3.5-5.0% | Ultra-high-net-worth, ski-in/ski-out | Ultra-premium, East Village exposure |
| Canyons Village | $700K-$1.8M | 4.5-5.5% | Resort zoning, established programs | Turnkey STR, accessible entry |
| Park Meadows / Lower Deer Valley | $1.3M-$2.8M | 3.5-5.0% | Dual resort proximity, residential character | Flexible STR/personal use |
| Prospector / Park City East | $700K-$1.4M | 4.5-6.0% | Local workforce option, less tourist density | More accessible entry, dual-purpose |
| Kimball Junction / Snyderville | $650K-$1.3M | 4.5-6.0% | Most affordable, I-80 access, Summit County rules | Lowest entry, different regulatory zone |
Expert Insight: “The number one mistake out-of-state investors make in Park City is buying based on the comp sale price without verifying the STR zoning and HOA rules for that specific building or neighborhood. I have seen buyers purchase a condo expecting to run it as a nightly rental, only to discover after closing that the HOA restricts rentals to 30-day minimums or prohibits them entirely. The zoning and HOA verification has to happen before you write an offer, not after. In Park City, that single piece of due diligence matters more than almost anything else in the purchase decision.” – Michael Reyes, Park City Resort Properties
3. Property Types
| Investment Goal | Best Property Type | Best Area | Minimum Capital |
|---|---|---|---|
| Lowest Entry / Hands-Off | Resort-zoned condo-hotel | Canyons Village | $225,000+ (30% down) |
| Maximum Demand Capture | Old Town townhome/condo | Old Town / Main Street | $420,000+ (30-35% down) |
| Ultra-Premium / Trophy Asset | Ski-in/ski-out SFH | Deer Valley / Empire Pass | $1.5M+ (30-40% down) |
| Most Affordable Entry | Condo/SFH in Summit County | Kimball Junction / Snyderville Basin | $195,000+ (30% down) |
Don’t guess the costs. Our Complete Renovation & Remodeling Cost Guide covers 400+ pages of project-by-project breakdowns with real contractor pricing ranges, useful for budgeting Old Town renovation projects or refreshing STR-ready interiors.
4. Cost Analysis
Acquisition Cost Breakdown (Park City)
| Expense Item | Typical Cost | Example ($1,000,000 Canyons Village Condo) | Notes |
|---|---|---|---|
| Down Payment | 30-40% (second home/investment) | $300,000-$400,000 | Second-home and STR-zoned condo financing typically requires higher down payments than primary residence financing |
| Closing Costs | 2-3% | $20,000-$30,000 | Utah closing costs below national average, though title insurance on higher-value properties scales accordingly |
| Home Inspection | $500-$900 | $650 | Older Old Town properties warrant especially thorough inspection given building age |
| HOA Dues | $500-$2,500/month | $800-$1,200/month | Resort-zoned condos often have higher HOA dues covering amenities, maintenance, and sometimes rental program participation |
| STR Furnishing / Setup | $15,000-$60,000 | $25,000-$40,000 | High-quality furnishings, linens, and amenities are essential to compete for premium nightly rates in this market; budget more than a typical residential STR |
| Reserves (12 months) | 12 months expenses | $35,000-$50,000 | Seasonal revenue requires larger reserves than monthly-leased residential property; recommend 12 months given revenue concentration in peak periods |
| TOTAL MINIMUM ENTRY | ~40-50% of value | $380,000-$520,000 | Substantially higher than any other market in this Utah series, both in absolute terms and as a percentage of purchase price |
Sample Revenue and Cost Analysis: Canyons Village Condo vs. Old Town Townhome vs. Deer Valley Ski-In/Ski-Out SFH
| Item | Canyons Village Condo (2BR) | Old Town Townhome (3BR) | Deer Valley Ski-In/Out SFH (5BR) |
|---|---|---|---|
| Purchase Price | $1,000,000 | $1,800,000 | $5,500,000 |
| Annual Gross STR Revenue | $75,000 | $115,000 | $310,000 |
| HOA Dues (annual) | -$12,000 | -$9,600 | -$24,000 |
| Property Taxes | -$7,500 | -$13,500 | -$41,250 |
| Insurance | -$2,500 | -$5,500 | -$18,000 |
| STR Management/Operator Fee (25-30%) | -$21,000 | -$31,000 | -$83,700 |
| Cleaning/Turnover (passed to operator above or separate) | Included in fee | Included in fee | Included in fee |
| Net Operating Income | $32,000 | $55,400 | $143,050 |
| Mortgage (35% down, 6.75%, 30yr) | -$50,600/yr | -$91,000/yr | -$278,000/yr |
| ANNUAL NET CASH FLOW | -$18,600 | -$35,600 | -$134,950 |
| Gross Yield (on price) | 7.5% | 6.4% | 5.6% |
| Total Return (10% appreciation) | ~22-26% | ~21-25% | ~18-22% |
All three Park City scenarios show negative annual net cash flow after debt service, which is normal and expected for highly leveraged second-home/investment property in this market. The gross yields of 5.6 to 7.5 percent are actually competitive when compared to the cap rates seen in other guides in this series, but the much higher purchase prices, larger absolute mortgage payments, and elevated HOA dues produce negative cash flow at standard leverage. Total return remains attractive primarily because of appreciation; Park City’s total return profile resembles the Cottonwood Heights “buy for the 10-year model” thesis but with operating revenue (STR income) partially offsetting the negative carry, unlike Cottonwood Heights’ pure long-term residential rental. Investors evaluating Park City should focus on total return over a multi-year hold rather than annual cash-on-cash return, and should stress-test these numbers against more conservative occupancy assumptions (a strong winter season but a slower summer, for example) before committing.
Expert Insight: “I tell every Park City buyer the same thing: do not run the numbers like this is a rental property in Sandy or Ogden. This is a resort asset. The income statement matters, but it is one input alongside appreciation, personal use value if you plan to use the property yourself, and the long-term scarcity of Park City real estate generally. If someone’s only criteria is ‘will the rental income cover the mortgage,’ Park City is probably not the right market for them, full stop. If their criteria includes appreciation, personal enjoyment, and a long time horizon, the income from STR operations is a meaningful offset to ownership costs, not the entire return.” – Michael Reyes, Park City Resort Properties
5. Legal Framework
⚠️ Complex, Jurisdiction-Specific STR Regulation: Verify Before You Buy
Unlike every other market in this Utah series, Park City’s regulatory environment is the primary determinant of whether a specific property can generate the revenue an investor expects. STR rules differ between Park City Municipal Corporation, unincorporated Summit County (including Snyderville Basin and Kimball Junction), and individual neighborhoods or developments with their own zoning designations (resort zoning vs. residential zoning) and HOA rules (which may further restrict or permit nightly rental regardless of underlying zoning). A property’s STR legality and any applicable caps, licensing requirements, or occupancy taxes must be verified for that specific address before any offer is made. This verification is more consequential to the investment outcome than any other due diligence step described in this guide.
Park City Municipal Corporation
- Zoning-Based STR Permission: Whether a property can operate as a nightly rental depends on its zoning designation. Resort-zoned areas (much of Canyons Village, parts of Old Town and other resort base areas) generally permit nightly rental. Residential zones may restrict or prohibit STR or require specific licensing.
- Business Licensing: Properties operating as STRs within Park City Municipal limits generally require a business license and compliance with applicable transient room tax collection and remittance.
- Transient Room Tax: Utah State and Summit County transient room taxes apply to short-term lodging revenue. STR operators must register, collect, and remit these taxes; many STR management platforms handle this automatically but the legal obligation rests with the property owner.
- HOA Rules Often More Restrictive Than Zoning: Even in resort-zoned areas, individual HOAs may impose additional restrictions (minimum stay requirements, rental caps, registration with a specific management company). The HOA’s governing documents (CC&Rs) are the operative document for many specific buildings.
Unincorporated Summit County
- Separate Regulatory Authority: Areas like Kimball Junction and Snyderville Basin fall under Summit County jurisdiction, not Park City Municipal Corporation. Summit County has its own land use code and STR regulations that differ from the municipal rules.
- Verify Current Summit County STR Ordinances: Summit County’s STR regulations have evolved over time and should be verified directly with Summit County Community Development for the specific parcel under consideration.
- Snyderville Basin Special Considerations: Some Snyderville Basin developments have their own planned unit development (PUD) rules that may be more restrictive or more permissive than baseline county rules; review the specific development’s governing documents.
Due Diligence Checklist Before Any Offer
- Confirm the property’s zoning designation with the relevant jurisdiction (Park City Municipal or Summit County)
- Obtain and review the HOA’s CC&Rs and any specific rental policy documents
- Confirm whether the HOA participates in or requires a specific rental management program
- Verify current STR licensing requirements and transient room tax obligations
- Ask the listing agent directly: “Is this specific unit currently operating as a nightly rental, and under what permit or zoning basis?”
| Regulation | Park City / Summit County | Comparison (Seattle) | Investor Impact |
|---|---|---|---|
| STR Permission | Zoning-dependent; resort zones generally permit, residential zones vary | City-wide STR licensing system with caps | Verify zoning per property before purchase; this is the central risk factor |
| HOA Authority | Often the operative restriction, can override or layer onto zoning | HOA rules also apply in condo buildings | Obtain and review CC&Rs before any offer; do not rely on zoning alone |
| Transient Room Tax | State and county taxes apply to nightly revenue | Similar lodging tax framework | Most STR platforms handle collection; owner retains legal obligation for registration |
| Jurisdiction Variation | Park City Municipal vs. Summit County rules differ | Single city jurisdiction | Identify which jurisdiction governs the specific property before assuming any rule applies |
6. Step-by-Step Park City Investment Playbook
Choose Your Park City Strategy
Turnkey Resort-Zoned Condo (Canyons Village)
Buy a resort-zoned condo with an established rental management program. Lowest operational involvement. Best entry point for first-time Park City investors who want exposure without learning the STR business from scratch.
Maximum Demand Capture (Old Town)
Buy in Old Town for maximum visitor demand and Sundance premiums. Requires either self-management or an independent STR management company. Highest demand density but more operational involvement than a condo-hotel program.
Trophy Asset (Deer Valley)
Buy ski-in/ski-out at Deer Valley or Empire Pass. Highest entry capital, highest nightly rates, ultra-high-net-worth tenant profile. Often combines personal use with STR income. Long-term hold for appreciation and brand-prestige asset.
Value Entry (Kimball Junction)
Buy in Snyderville Basin / Kimball Junction for the lowest entry capital in the broader Park City market. Verify Summit County (not Park City Municipal) STR regulations apply. Good for investors who want Park City market exposure with the lowest capital commitment.
Build Your Park City Team
- Park City-Specialist Agent: Must be deeply familiar with zoning distinctions between Park City Municipal and Summit County, HOA rental policies for specific buildings, and current STR performance data for comparable properties. A generalist Wasatch Front agent will not have this knowledge; this market requires a true Park City specialist.
- Real Estate Attorney with HOA/CC&R Experience: Before any offer, an attorney should review the specific HOA’s CC&Rs and any rental policy addenda. Given the entry prices involved, this legal review cost is a small fraction of the transaction value and is essential.
- Local STR Management Company: Unless purchasing within an established condo-hotel program, identify and vet an STR management company with a track record in the specific neighborhood. Ask for their average occupancy and revenue performance for comparable units, their fee structure, and their approach to Sundance-week pricing.
- Tax Professional Familiar with Resort Property: Transient room tax registration and remittance, potential bonus depreciation strategies for STR property (consult a CPA on current tax law), and second-home versus investment property tax treatment all require a tax professional experienced with resort real estate, not a general practitioner.
Expert Tip: Before engaging any agent, ask them directly: “Walk me through the zoning and HOA verification process for a specific property I am considering.” A true Park City specialist will immediately know what documents to request and what questions to ask the HOA. An agent who is vague on this process or suggests “we can figure that out after we are under contract” is not the right agent for a market where this single issue can determine whether your investment thesis is even viable.
Park City-Specific Due Diligence
Regulatory and Financial Checks
- Confirm zoning designation (Park City Municipal vs. Summit County) and whether STR is permitted
- Obtain and review HOA CC&Rs and any specific rental policy documents
- Request historical STR revenue data for the specific unit if available, or comparable units in the same building/development
- Confirm property tax assessment basis (Utah has a primary residence property tax reduction that does not apply to investment/STR properties)
- Verify HOA dues trajectory and any planned special assessments
Physical and Market Checks
- Measure actual walking distance/time to lift access if ski-in/ski-out or near-resort positioning is part of the thesis
- For older Old Town properties: thorough structural, electrical, and plumbing inspection given building age
- Assess furnishing condition and what STR-ready setup investment will be required
- Review comparable nightly rates and occupancy for similar units using STR market data tools (AirDNA or similar) for the specific micro-location
- Model revenue assuming a realistic occupancy curve (strong winter, moderate summer, weaker shoulder seasons) rather than peak-season rates applied year-round
Optimizing Revenue Across Park City’s Seasonal Calendar
Unlike every residential rental market in this series, Park City revenue optimization is about managing a seasonal calendar, not filling a vacancy:
- Winter season (December-March) pricing strategy: This is the primary revenue period. Pricing should reflect demand peaks around holidays (Christmas/New Year, Presidents Day) with premium rates, and slightly lower rates during January non-holiday weeks (except Sundance).
- Sundance week (late January): Set rates 3-5x normal winter rates with extended minimum-stay requirements (often a full week). Book Sundance well in advance; this is the most predictable high-revenue period of the year and demand for it begins months ahead.
- Summer season (June-September): Park City’s summer mountain biking, golf, and event calendar (concerts, festivals) support a genuine summer season, unlike single-season resort towns. Price summer competitively but recognize it will generally be below winter peak rates.
- Shoulder seasons (April-May, October-November): The lowest-demand periods. Some owners use shoulder seasons for personal use, maintenance, or longer-term furnished rentals to local workforce or relocating professionals rather than leaving units vacant at low STR rates.
- Dynamic pricing tools: Most professional STR management companies and platforms use dynamic pricing algorithms that adjust nightly rates based on demand signals (booking pace, event calendars, competitor pricing). Verify your management approach includes this; static pricing leaves significant revenue on the table in a market this seasonally variable.
7. Financing Options for Park City
| Loan Type | Down Payment | Rate Premium | Best For | Park City Note |
|---|---|---|---|---|
| Jumbo Second Home | 20-30% | +0.25-0.5% vs primary | Buyers who will use the property personally part of the year | Most Park City properties require jumbo financing given price points well above conforming limits. Second-home rates are generally more favorable than pure investment property rates if personal use applies. |
| Jumbo Investment Property | 30-40% | +0.75-1.5% vs primary | Pure investment, no personal use | Higher down payment and rate premium than second-home financing; lenders treat declared STR investment properties differently than occasional-use second homes |
| Asset-Based / Portfolio Lender | 30-40% | Varies | High-net-worth buyers, complex income situations | For ultra-premium properties (Deer Valley, Empire Pass), private banks and wealth management lending arms often provide more flexible underwriting based on overall assets rather than standard income documentation |
| Cash Purchase | 100% | N/A | High-net-worth buyers | A meaningful share of Park City transactions, particularly at the Deer Valley/Empire Pass tier, are cash purchases. Cash buyers can move faster in competitive situations and avoid financing-related underwriting questions about STR income. |
| DSCR Loan | 30-35% | +1.5-2.5% | Self-employed STR investors | Some DSCR lenders now underwrite based on projected STR income (using AirDNA or similar data) rather than only long-term lease income; confirm the lender’s approach to STR income documentation specifically, as this is a newer and less standardized practice than traditional DSCR underwriting on long-term rentals |
Second Home vs. Investment Property Classification: How a Park City property is classified for financing purposes (second home vs. investment property) has meaningful implications for both the loan terms (down payment and rate) and ongoing costs (Utah’s property tax structure provides a primary residence exemption that does not apply to either second homes or investment properties, but the specific classification can affect insurance requirements and other factors). If you intend to use the property personally for a portion of the year while also generating STR income during other periods, discuss with your lender how this dual-use intent affects financing classification, and with your tax professional how it affects tax treatment of expenses and depreciation. This is a more complex determination than in any purely investment-oriented market in this series.
8. Frequently Asked Questions

Knowledge Quiz: Park City Real Estate Investment
Open Quiz
5 quick questions on what you just learned about Park City investing
1) What is the single most important due diligence step in Park City that does not have an equivalent in the other Utah markets covered in this series?
Answer: B
The guide repeatedly emphasizes that Park City’s central risk factor is “permission risk” rather than “market risk.” Unlike every other market in this series where the question is whether demand exists for a rental, in Park City visitor demand is essentially guaranteed given the resort’s destination status. The question that determines investment viability is whether a specific property, given its zoning (Park City Municipal vs. Summit County) and its HOA’s governing documents, is legally permitted to operate as a nightly rental. The guide states this verification “is more consequential to the investment outcome than any other due diligence step described in this guide” and must happen before any offer is made.
2) How should Sundance Film Festival revenue be incorporated into an investment underwriting model for a Park City property?
Answer: D
The guide is explicit that Sundance revenue, while real and significant (3 to 5 times normal rates for about a week, representing 8 to 15 percent of annual revenue for well-positioned properties), should be additional upside layered onto a realistic base-case model built on regular seasonal performance. The guide warns: “If the investment only works assuming Sundance-level revenue for multiple weeks per year, the underwriting is unrealistic.” It also notes the long-term location of Sundance has been periodically reconsidered by organizers, so investors should not build their entire thesis around it, while also not ignoring it as a genuine and predictable revenue contributor for properties well-positioned near festival venues (primarily Old Town).
3) Why do all three sample Park City scenarios (Canyons Village condo, Old Town townhome, Deer Valley SFH) show negative annual cash flow despite gross yields of 5.6-7.5%, and why does the guide say this is normal?
Answer: A
The guide explains that gross yields of 5.6 to 7.5 percent are actually competitive compared to cap rates in other guides in the series, but Park City’s much higher absolute purchase prices, elevated down payment requirements (30-40% vs. 25% in metro markets), and higher HOA dues produce large absolute carrying costs that exceed NOI at standard leverage. The guide explicitly compares this to the Cottonwood Heights “buy for the 10-year model” thesis, where total return depends primarily on appreciation, but notes Park City STR income provides operating revenue that partially offsets carrying costs in a way pure long-term residential rental in Cottonwood Heights does not. The guide recommends focusing on multi-year total return rather than annual cash-on-cash return.
4) What distinguishes the Deer Valley East Village expansion as an investment opportunity within the current Park City market cycle?
Answer: C
The guide describes the Deer Valley East Village expansion as “the closest thing to a ‘ground floor’ opportunity in this otherwise mature market,” drawing the analogy to early investment in a resort’s expansion area before it becomes fully established. It notes major resort expansions of this scale are infrequent, and historically investors who buy early in such expansion areas have captured appreciation as the area matures. However, the guide is equally clear about the risks: “development-stage real estate carries timeline uncertainty (construction delays, phasing changes) and the new area’s eventual character and amenity level is not yet fully realized.” The guide recommends researching the current development timeline directly with Deer Valley Resort and the Park City planning department, and evaluating how close any specific opportunity is to already-operational infrastructure.
5) How does Utah’s property tax structure specifically affect Park City investment property compared to an owner-occupied primary residence?
Answer: B
The guide explains that Utah provides a primary residence property tax reduction that requires the property to be the owner’s primary residence to qualify. Since the vast majority of Park City real estate consists of second homes and investment properties, these do not qualify for the reduction and are taxed at the full assessed rate, higher as a percentage of value than an equivalent owner-occupied primary residence elsewhere in Utah. The guide specifically flags a practical due diligence trap: if a current seller has been claiming a primary residence exemption that would not transfer to an investor-buyer, the buyer’s actual ongoing property tax bill could be higher than the seller’s current bill suggests, and this detail “is easy to miss and can meaningfully affect the cost analysis.”
Work With a Local Expert in Park City
We are building a verified network of real estate professionals across every market we cover.

About Our Expert Network
We are finalizing partnerships with verified real estate professionals across every market featured on Builds and Buys.
Our local Park City specialists offer:
- Zoning verification across Park City Municipal and Summit County jurisdictions
- HOA CC&R review and rental policy analysis for specific buildings
- STR management company referrals with track records by neighborhood
- Sundance and seasonal revenue performance data for comparable properties
- Jumbo and asset-based lender connections for second-home and investment financing
- Deer Valley East Village development timeline guidance
Services Covered
- Property sourcing and acquisition
- Zoning and HOA verification
- STR revenue projection
- Investment analysis and underwriting
- Jumbo/asset-based financing referrals
- Furnishing and STR setup guidance
- Legal and CC&R review
- STR management referrals
- Tax professional referrals
- Insurance and inspection referrals
- Transient tax registration guidance
- Exit strategy planning
Get Connected or Join Our Network
Looking for a Park City investment specialist? Reach out and we will connect you with the right professional.
Contact us at support@buildsandbuys.com
Find Specialized Park City Real Estate Professionals
Ready to Invest in Park City?
Park City stands apart from every other market in this Utah series, and that is precisely the point. This is not a residential rental market with a nice view; it is a destination resort hospitality business with real estate as the underlying asset. The investment thesis rests on three durable pillars: a year-round visitor base spanning winter skiing, Sundance, and summer recreation that no other Utah market can claim; a globally recognized brand built over decades through Vail Resorts ownership, Deer Valley’s exclusivity, and Sundance’s cultural prestige; and a permanently constrained land supply driven by mountain terrain and Summit County conservation policy. The capital requirements are Utah’s highest by a wide margin, and the operational model, zoning verification, HOA review, seasonal revenue management, and STR-specific financing, is unlike anything else in this series. For investors with the capital and the willingness to operate (or professionally manage) a hospitality business rather than a residential rental, Park City offers a combination of brand prestige, appreciation history, and destination demand that exists nowhere else in Utah.
Continue Your Research
Utah State Guide
See how Park City compares to the full Utah investment landscape, from metro residential markets to other resort communities.
Cottonwood Heights Guide
Compare Park City’s STR resort model to Cottonwood Heights’ long-term professional rental approach to canyon access.
144-Lesson Course
University-level real estate education covering financing, law, strategy, and management.
For further guidance, explore our State-by-State Investor guides, browse our expert articles, or follow our Step-by-Step Investment Guide.